Get Accurate Renters Insurance Quotes California in Minutes
Navigating California's high cost of living can make any extra expense feel like a burden, but what if one small monthly payment could save you thousands down the line? That's the real value of renters insurance—a surprisingly affordable financial safety net for everything you own. Getting renters insurance quotes in California is the first step toward securing that protection and peace of mind.
Why Renters Insurance in California Is a No-Brainer
When you're a renter in the Golden State, you're used to seeing high price tags. Housing costs are steep, and it's natural to assume any insurance policy would follow suit. But here’s some good news: when it comes to renters insurance, California tenants actually catch a break.
Believe it or not, Californians enjoy some of the most affordable renters insurance premiums in the entire country.
California Renters Insurance at a Glance
This quick table shows just how affordable coverage is in California compared to the rest of the US.
| Metric | California Average | National Average |
|---|---|---|
| Average Monthly Cost | $19 per month | $23 per month |
| Average Annual Cost | $228 per year | $276 per year |
| Annual Savings | $48 vs. national average | N/A |
As you can see, you get to keep an extra $48 in your pocket each year—a small but welcome relief in a state known for its high cost of living.
Don't Mistake Your Landlord's Policy for Your Own
I see this all the time: tenants assume their landlord’s insurance has them covered. It’s a common and costly mistake. The property owner's policy is designed to protect their investment—the building itself. It covers the roof, the walls, and the physical structure, but it does absolutely nothing for your personal property.
Imagine a pipe bursts or a fire breaks out. If your laptop, furniture, and clothes are destroyed, you're on the hook for replacing everything out of pocket. We're talking about thousands of dollars in sudden, unexpected costs. This is precisely why more landlords are making renters insurance a mandatory part of the lease. Taking a look at a free rental agreement template can give you a better idea of these common requirements.
Key Takeaway: Renters insurance bridges a critical gap. It protects your belongings, provides liability coverage if someone gets hurt in your home, and even pays for temporary housing if your place becomes unlivable. It's a small price for invaluable peace of mind.
Getting the right coverage shouldn't be a hassle. At Mai & Associates, we make comparing renters insurance quotes in California simple. We’ll help you find a policy that fits your budget and covers your specific needs, whether you're looking for renters, home insurance, auto insurance, or life insurance.
What’s Actually Inside a California Renters Insurance Policy?
When you start comparing renters insurance quotes in California, it's easy to just focus on the final price. But what you're really looking at is a bundle of different protections, each one designed to shield you from a specific kind of financial hit. Think of it less as a single product and more as your personal financial safety net.
Let's break down the three main parts of a standard renters policy. Getting a handle on these is the key to making sure you're not just insured, but properly insured.
Personal Property: Covering Your Stuff
This is the part everyone thinks of first. It’s what protects your personal belongings—your couch, TV, clothes, laptop, kitchen gear, you name it—if they’re stolen or damaged by something like a fire or a burst pipe. If someone breaks into your apartment and makes off with your computer and jewelry, this is the coverage that helps you replace them.
So, how much do you need? Don't just pull a number out of thin air. You almost certainly own more than you realize. The best way to get a real number is to do a quick home inventory. Seriously, just walk through your place with your phone, recording a video and pointing out your big-ticket items. You might be shocked to find your things are worth $20,000 or more. This little exercise ensures you buy enough coverage to actually make you whole again after a disaster.
Liability Protection: When Accidents Happen
This is your financial bodyguard. Liability coverage steps in if you're on the hook for someone getting hurt in your apartment or if you accidentally damage someone else’s property. Imagine a friend comes over, slips on a wet spot on your kitchen floor, and breaks their wrist. Your liability coverage can help pay for their medical bills and any legal fees if they decide to sue.
It's easy to think, "That'll never happen to me." But a simple, everyday accident can quickly turn into a financial nightmare that puts your savings and even future income at risk.
This is exactly why most landlords now require you to have at least $100,000 in liability coverage. It's not just about protecting their property; it's about protecting you from a lawsuit that could follow you for years. Higher limits are usually available for just a few extra dollars a month, and they're worth every penny. You can dive deeper into this topic with this helpful guide on home contents insurance for tenants.
Additional Living Expenses: When You Can't Go Home
What if a fire, a major leak, or another disaster forces you out of your apartment? You can't live there, but you still have to pay rent. Where do you go? This is where Additional Living Expenses (ALE) coverage, sometimes called "Loss of Use," becomes a lifesaver.
ALE is designed to cover the extra costs you face when you're displaced, like:
- A hotel room or a short-term rental.
- The cost of eating out because you don't have a kitchen.
- Other essentials, like paying for a laundromat.
This coverage lets you maintain a sense of normalcy without having to burn through your emergency fund during an incredibly stressful time. To see what this looks like in a real policy, take a look at our California renters insurance guide for more specifics.
How to Get an Accurate Renters Insurance Quote
Getting a truly accurate renters insurance quote in California isn't about clicking a magic button. It's about a little prep work. The better the information you give an insurance provider, the more precise your quote will be, which means no surprises later on. Think of it as creating a simple "cheat sheet" for your rental life before you start shopping around for California insurance.
Insurance carriers use specific details to figure out their risk, and that risk calculation is what determines your premium. By gathering a few key pieces of information upfront, you’ll make the whole process smoother and faster, whether you're filling out an online form or talking directly with one of our agents here at Mai & Associates.
Your Personal Quote Checklist
Before you start requesting quotes, take a few minutes to pull these details together. Trust me, it makes a world of difference and ensures the prices you see are actually for your specific situation.
- Your Exact Address: This one is non-negotiable. Insurers need your specific address to check everything from local crime statistics to how close you are to the nearest fire station. A quote for "San Diego" is a wild guess; a quote for a specific address in North Park will be the real deal.
- Building Safety Features: Does your complex have a security gate? Do you have deadbolts and smoke alarms? These little things can add up to real discounts, so make a note of them. Every bit helps.
- A Rough Value of Your Stuff: You don't need a perfect, itemized list just yet, but try to get a ballpark figure. Most renters I talk to initially guess around $10,000, but after they do a quick mental inventory of their furniture, clothes, and electronics, they realize it's often closer to $25,000 or more.
- Details About Your Pets: Yep, Fido and Fluffy matter. When it comes to liability, some dog breeds are unfortunately considered higher risk by insurance carriers, and that can impact your rate. It's crucial to be upfront about your pets to make sure you're properly covered if an incident ever happens.
This quick preparation helps an agent or online tool accurately price out the core components of your policy.
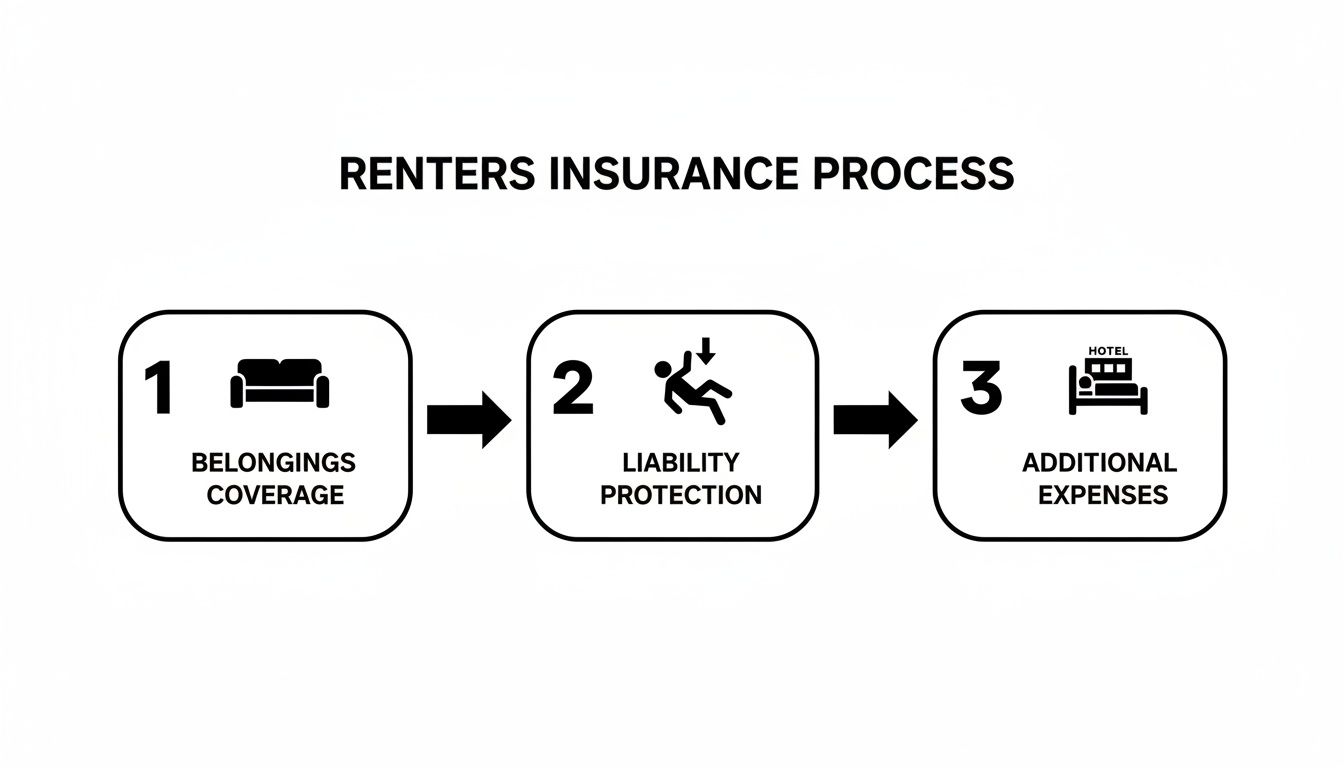
As you can see, a quote is really a combination of three key protections: safeguarding your belongings, covering your personal liability, and providing a safety net for extra expenses if you're displaced. Having your info ready makes this process seamless.
By gathering these details beforehand, you're not just getting a price—you're actively building a policy. It’s the difference between a generic estimate and a personalized quote that gives you real protection for your life in California.
Getting a Handle on California’s Unique Risks: Wildfires and Earthquakes
There’s no denying the perks of living in California. But alongside the sunshine and scenery, we have to deal with some serious natural risks. When you’re shopping for renters insurance quotes in California, you absolutely must ask how your policy will respond to wildfires and earthquakes. Your standard policy isn't built to handle everything the Golden State can dish out.
The good news? A standard renters policy does cover damage from fire, and that includes wildfires. If a fire damages your stuff—or even if smoke ruins your furniture and clothes—your personal property coverage is there to help you replace it. But that's where the good news ends for standard coverage.
The Big Exclusions: What Your Policy Won’t Cover
Here’s a detail that trips up a lot of renters: standard policies almost always exclude damage from earthquakes and floods. This is a massive gap in your financial safety net, and it's one you can’t afford to ignore, whether you're buying renters or home insurance in California.
Just picture it. An earthquake shakes your Glendale apartment, and your brand-new TV, laptop, and glassware all come crashing down. Without specific earthquake coverage, you're on the hook for replacing every single one of those items yourself. This is exactly why you need to look beyond a basic, off-the-shelf policy.
How to Add the Right Protections
To be truly covered, you'll need to add some specific protections to your insurance plan. This is a crucial conversation to have when you're getting quotes, as it's not an automatic feature.
You generally have two paths to take:
- Earthquake Endorsement: Think of this as an add-on to your renters policy. For a small increase in your premium, it extends protection to your personal belongings if they’re damaged in a tremor.
- Separate Earthquake Policy: In some situations, especially if you're in a high-risk zone, a completely separate policy might be necessary. This gives you dedicated coverage with its own limits and deductible.
Figuring this out can get complicated. For instance, if you live in an area prone to wildfires, you might need to look at specialized options like the California Fair Plan. This is where leaning on the expertise of a local agent really pays off. As we discuss in our guide to California home insurance, local knowledge is essential for closing these dangerous gaps.
An independent insurance partner like Mai & Associates can look at your exact address, understand your real-world risk, and find the right solution. We help clients find the right earthquake endorsement or source a separate policy, making sure you're protected from the ground up, whether you're in Escondido or up the coast.
Don't just assume your basic policy has you covered. For genuine peace of mind in California, you have to tackle the earthquake and wildfire risks head-on. Taking this extra step ensures your financial safety net is actually strong enough to catch you when you need it most.
Smart Ways to Lower Your Insurance Premiums
Getting great coverage doesn't have to break the bank. Even though renters insurance in California is already one of the most affordable policies you can buy, there are always ways to shave a few more dollars off your monthly premium. With a few strategic moves, you can lock in a fantastic rate without giving up the protection you need for your California insurance needs.
Think of it this way: your premium is a direct reflection of risk. The less risk you pose to the insurance company, the less you'll pay. Simple as that. Here’s how you can show them you’re a great bet.
Adjust Your Deductible for a Quick Win
The fastest way to see an immediate drop in your premium? Tweak your deductible. This is the amount you pay out of pocket before your insurance kicks in to cover the rest. It's a straightforward trade-off: a higher deductible equals a lower monthly payment.
For example, just by increasing your deductible from $250 to $500, you might see your premium go down by 5-10%. If you're comfortable with a $1,000 deductible, the savings could be even more significant. The trick is to choose a number you could actually come up with on short notice without causing financial stress. A $1,000 deductible won't do you much good if you don't have that amount tucked away in an emergency fund.
A higher deductible is essentially a bet on yourself. You're betting you won't have to file a claim, but you're financially prepared to cover a bigger slice of the pie if you do. For many careful renters, it's a smart financial move.
The Power of the Policy Bundle
One of the biggest discounts out there comes from bundling your policies. It’s exactly what it sounds like: buying more than one type of insurance from the same company. When you pair your renters insurance with a California car insurance policy, for instance, insurers will often give you a serious discount on both. They love loyalty, and it’s more efficient for them to manage one customer with multiple policies.
The savings here are no joke, often landing in the 10% to 20% range. At Mai & Associates, we make this incredibly easy since we're a full-service agency. We can shop for your renters insurance, auto insurance, and even life insurance all at once to find the absolute best bundle that maximizes your discounts. This single strategy is often the most powerful tool for cutting your total insurance bill.
Don't Overlook These Common Discounts
Beyond bundling, a whole host of other discounts are usually on the table. They might seem small on their own, but when you start stacking them, they can make a real dent in your final premium.
Many renters miss out on savings simply because they don't know what to ask for. Below is a quick look at some of the most common discounts available.
Common Discounts to Lower Your Renters Insurance Premium
| Discount Type | Estimated Savings | How to Qualify |
|---|---|---|
| Safety Devices | 5-15% | Install and maintain smoke detectors, fire extinguishers, and carbon monoxide detectors. |
| Protective Devices | 5-20% | Have deadbolt locks, a central burglar alarm, or a gated community entrance. |
| Claims-Free History | 10-20% | Maintain a record of no claims for a set period (usually 3-5 years). |
| Pay-in-Full | 5-10% | Pay your entire annual premium upfront instead of in monthly installments. |
Never assume these discounts are automatically included in your quote. When you're working with your agent at Mai & Associates to get your renters insurance quotes in California, make sure you mention every single safety feature your apartment or home has. Every little detail helps us find every last dollar of savings you deserve.
Getting Your Free Quotes from Mai & Associates
Ready to see how affordable peace of mind can be? We've made the process of getting personalized renters insurance quotes in California as straightforward as possible. No jargon, no runaround—just clear, actionable information so you can make the right choice for your life and budget.
Your Path to a No-Obligation Quote
Instead of spending an afternoon bouncing between different insurance company websites, let us do the legwork for you. We’ll shop your policy with multiple top-rated carriers at once, ensuring you see the most competitive options available for your renters insurance, auto insurance, home insurance, or life insurance.
Here’s what you can expect when you reach out to our team:
- Same-Day Quotes: We know you're busy. You’ll see your numbers quickly, often on the same day you contact us.
- Prompt Expert Advice: A licensed agent will get back to you within 24 hours to walk you through your options and answer any questions.
- Multilingual Support: We’re proud to serve California’s diverse communities and offer assistance in English, Spanish, Armenian, Russian, and Vietnamese.
The best part? There's absolutely no pressure. Our quotes are completely free and come with no strings attached. We want you to feel confident and informed, not rushed into a decision.
With offices across the state, we offer the local expertise that truly makes a difference. When you're ready to take the next step and protect what matters most, our team is here to help.
The easiest way to start is by requesting your free California insurance quote online. It only takes a few minutes.
California Renters Insurance: Your Questions Answered
Even after you've done your homework, a few lingering questions about renters insurance are completely normal. Getting clear, straightforward answers is the final step to picking a policy with confidence. Let's walk through some of the most common things people ask when they're getting renters insurance quotes in California.
Is Renters Insurance a Legal Requirement in California?
No, the state of California doesn't have a law on the books forcing tenants to buy renters insurance.
However, your landlord absolutely can require it as part of your lease. This is a very common practice. It’s not about them being difficult; it's a way to ensure you're covered if you accidentally cause damage, which in turn protects their investment. Always double-check your lease agreement to see what's required before you sign.
How Much Personal Property Coverage Do I Really Need?
This is the million-dollar question, and most people guess way too low. The best way to figure out a realistic number is to grab your phone and take a quick video of your apartment.
Walk through each room, talking through what you see—your laptop, that new couch, your TV, all your clothes, even the stuff in your kitchen cabinets. You'll probably be shocked to realize your belongings add up to $20,000 to $30,000 or more. It’s always smarter to have a little more coverage than you think you need than to be caught short after a disaster.
A Pro Tip From Experience: The little things add up fast. Think about replacing every fork, towel, book, and decorative pillow. Creating a home inventory list now will be a lifesaver if you ever have to file a claim.
Does My Policy Cover My Roommate's Belongings?
This is a big one. A standard renters policy covers you, your spouse, and any relatives living with you. It does not cover your roommate or their personal belongings.
To be protected, your roommate needs to get their own, separate renters insurance policy. Sharing a policy can get messy, so having individual ones is always the cleanest and safest approach.
You can find more in-depth answers to common questions in our full guide to frequently asked questions about California insurance.
What's the First Thing I Should Do to File a Claim?
If something happens, the absolute first step is to make sure everyone is safe and to call for emergency help if necessary.
Once the immediate danger has passed, document everything. Use your phone to take lots of photos and videos of the damage from every possible angle. Then, get in touch with your insurance agent or carrier right away to start the claims process. They'll walk you through exactly what to do next.
Ready to find a renters insurance policy that fits your budget and gives you real peace of mind? The team at Mai & Associates is here to help. We can help you compare policies from top-rated carriers for your renters insurance, auto insurance, home insurance, and life insurance needs. Visit us online to get your no-obligation quote today at https://cahomeauto.com.