Renters Insurance California Reddit: 2026 Guide to Coverage
You're probably here because you opened Reddit to answer one simple question, then got buried in twenty threads arguing about whether renters insurance in California is a scam, a lease requirement, or the cheapest financial protection you can buy.
One post says “just get the lowest premium.” Another says your landlord can't force it. A third warns that one claim will haunt you forever. Then someone in Los Angeles says wildfire risk changes everything, and someone in San Francisco says their policy was easy until they read the exclusions. That's the problem with the Renters Insurance California Reddit search spiral. The experiences are real, but they're fragmented.
California insurance has more moving parts than most renters expect. That matters whether you're focused on renters insurance, comparing home insurance options for a future move, bundling with auto insurance or car insurance, or trying to keep your overall protection plan in line with life insurance and household risk. Reddit is useful for spotting red flags. It's not great at turning scattered anecdotes into a clean decision.
The Reddit Rabbit Hole of California Renters Insurance
A common California renter story goes like this. You sign a lease, your landlord asks for proof of coverage, and suddenly you're comparing screenshots from Reddit comments instead of reading the policy form in front of you. One person says they pay next to nothing. Another says the only thing that matters is liability. A third says landlord-required coverage is just a money grab.
The confusion makes sense because renters insurance feels small until something goes wrong. Then it stops being a line item and turns into a claim, a hotel stay, a stolen laptop, or a liability problem with actual legal consequences.
Here's the hard part. In California, only 49% of rental households have a renters policy, even though the average cost is about $19 per month ($228 annually), which is lower than the national average, according to ResidentShield's California renters insurance overview. That gap tells you a lot. Plenty of renters know the product exists, but many still don't buy it or don't understand what they're buying.
Reddit is good at surfacing anxiety. Insurance decisions get better when you pair that anxiety with actual policy language.
The smart move isn't ignoring Reddit. It's using it the right way. Treat Reddit as a place to collect questions, not final answers. Then pressure-test those questions against how California policies work, especially around exclusions and lease requirements.
If you want a broader grounding on California coverage issues before you compare policies, a practical starting point is this set of California insurance guides. It helps frame renters insurance in the bigger context of property, liability, and regional risk.
Decoding What Your Policy Actually Covers
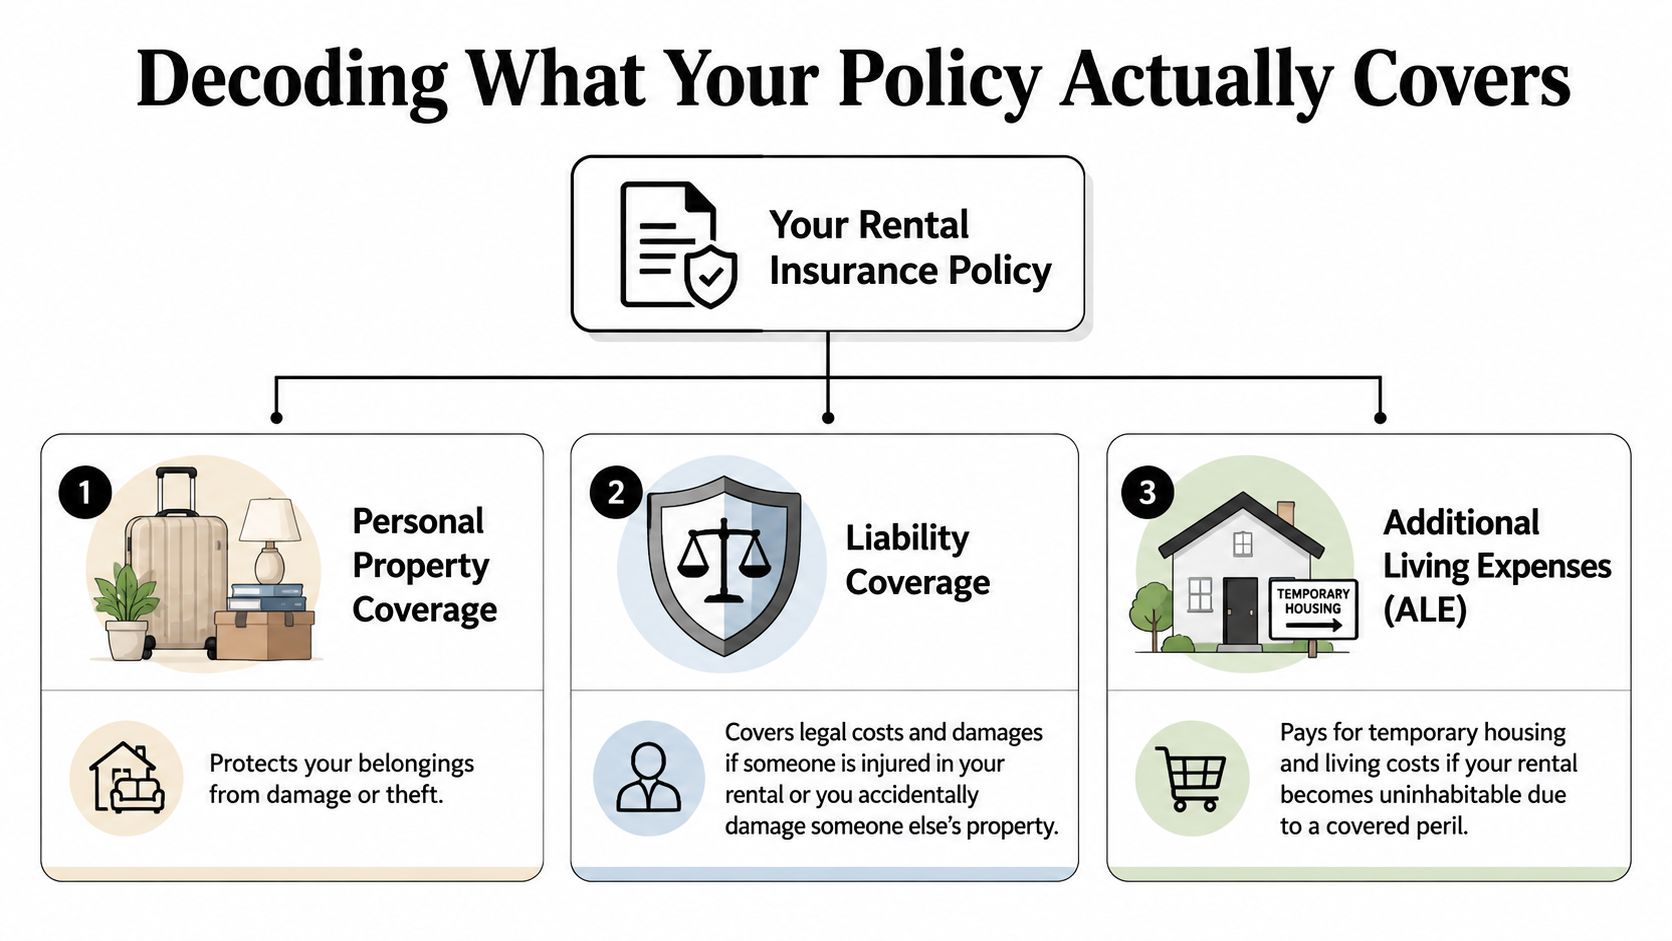
Most renters insurance policies look more complicated than they are. Strip away the legal phrasing, and you're usually dealing with three core buckets: personal property, liability, and additional living expenses.
Many landlords can require coverage as part of the lease even though California state law doesn't mandate it. A standard policy with $100,000 in personal liability and $30,000 in personal property costs about $19 per month in California, according to Insurify's renters insurance guidance.
Personal property means your stuff, not the building
This is the part most renters care about first. If a covered event damages or steals your belongings, this coverage helps replace them. Think clothes, furniture, kitchen items, electronics, and the random things you'd hate to repurchase all at once.
A lot of renters make the same mistake. They assume the landlord's policy protects whatever is inside the unit. It usually protects the building owner's interest in the structure, not your couch, desk, mattress, or headphones.
A quick home inventory matters here. Not because it's glamorous, but because people consistently underestimate the value of everyday belongings.
Liability is the part people ignore until they need it
Liability coverage acts like a legal and financial shield if someone gets hurt in your rental or if you accidentally damage someone else's property. This is often the least understood part of a renters policy and one of the most valuable.
Examples include a guest slipping in your apartment, your dog creating an injury claim, or water from your unit damaging a neighboring space. If you want a useful non-renters example of how messy property loss can become, this breakdown of homeowners water damage claims is worth reading because it shows how important the exact cause of damage is in insurance, not just the fact that damage happened.
Practical rule: If you can't explain what triggered the loss, you probably can't predict whether the policy will respond.
Additional living expenses help when the unit can't be lived in
This piece gets less attention on Reddit, but it matters. If a covered loss makes your rental uninhabitable, the policy may help with temporary living costs while repairs happen. That can include lodging and related expenses, subject to policy terms.
Renters insurance connects to the rest of your insurance life. If you already compare car insurance, auto insurance, home insurance, or life insurance with a careful eye for exclusions, apply that same discipline here. Definitions matter. Covered causes matter. Limits matter.
If you run into unfamiliar terms, a plain-English insurance glossary for California consumers can save you from guessing.
California Exclusions Wildfire and Earthquake Gaps
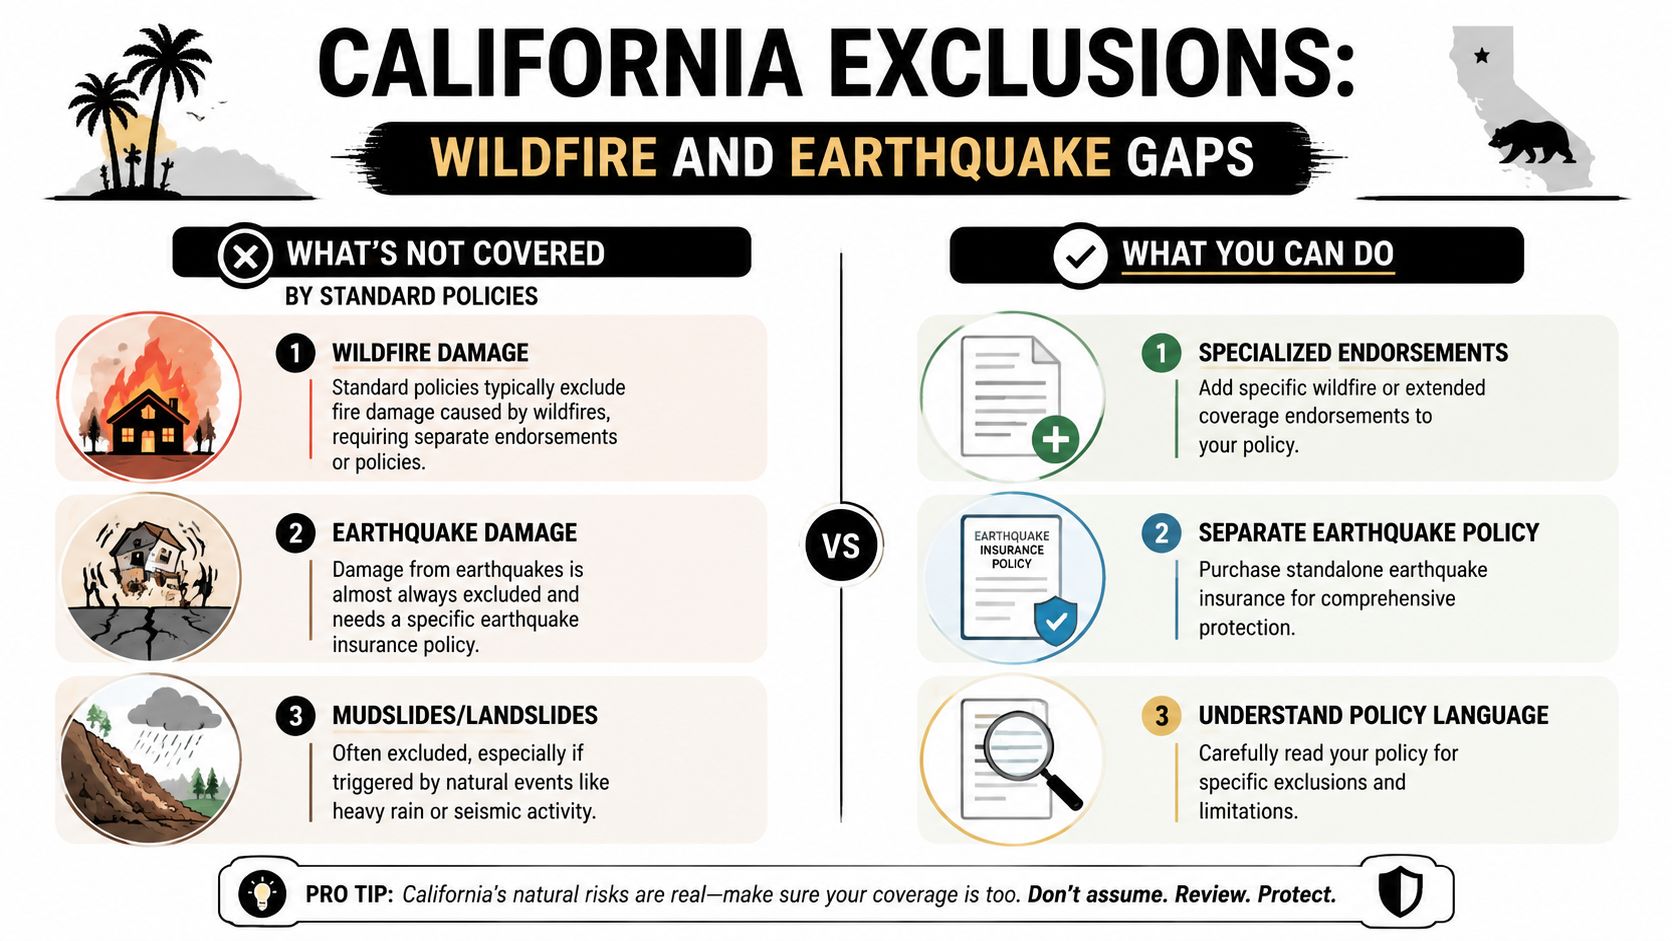
The most dangerous assumption a California renter can make is thinking a standard policy is automatically “good enough.” In many parts of the state, that assumption falls apart as soon as you look at earthquakes and wildfire language.
Renters often buy a policy, see the word “fire,” and stop reading. That's where trouble starts.
Earthquake coverage is where false confidence shows up
A standard renters policy typically excludes earthquake damage unless there's a specific endorsement or separate coverage structure that applies. Renters also often fail to verify whether an “optional earthquake” feature protects their personal property or relates more broadly to the building context. NerdWallet notes that renters frequently miss this distinction, and it also warns about wildfire exclusion issues in high-risk ZIP codes in its California renters insurance analysis focused on exclusions and gaps.
That building-versus-belongings distinction matters more for renters than most online discussions admit. Your landlord insures the structure. You need clarity on your own inventory.
Ask direct questions like these:
- Does the earthquake option cover my personal belongings? Don't settle for vague language like “earthquake available.”
- Is the coverage added by endorsement or through a separate form? Those are different things.
- What losses are still excluded? Optional coverage doesn't always mean broad coverage.
Wildfire wording can get slippery fast
Reddit threads often simplify wildfire coverage into “covered” or “not covered.” Real policies are more nuanced. In higher-risk California areas, renters can run into policy terms, restrictions, or exclusions they didn't expect.
The red flag is not just the exclusion itself. It's the renter who never knew to check for one.
Use this quick filter when reviewing a quote:
| What to check | Why it matters |
|---|---|
| Covered perils language | Tells you whether fire-related loss is treated broadly or with carve-outs |
| ZIP code underwriting limits | High-risk areas can change eligibility or available options |
| Endorsements and riders | Some gaps can be narrowed only if they're added intentionally |
| Claim examples from the agent or carrier | Real scenarios reveal more than marketing copy |
What works better than guessing
The best approach is boring and effective. Ask for the actual coverage summary. Ask whether earthquake damage to your personal property is excluded unless endorsed. Ask whether wildfire-related losses face any location-based limitations. Then get the answer in writing.
If the answer sounds fuzzy on the phone, assume it will feel worse during a claim.
This is one reason California renters should pay attention to broader property insurance dynamics, not only renters forms in isolation. The same regional risk pressures that affect renters also shape the California home insurance market, especially in wildfire-prone areas.
Reddit Pro Tips and Red Flags Vetted by an Agent
Reddit gets a lot right. It also compresses important trade-offs into one-liners that sound smarter than they are. Here are the themes I'd keep from the Renters Insurance California Reddit ecosystem, along with the parts I'd treat carefully.
Good Reddit advice that usually holds up
Some recurring Reddit habits are solid.
- Shop more than one carrier. This is smart because pricing and appetite vary a lot between insurers.
- Read the lease before you buy. Landlords often set minimum requirements, and buying the wrong limit just creates a second task.
- Document your belongings. A simple phone video of each room makes future claims easier.
- Don't obsess only over premium. The cheapest quote can hide narrow coverage, weak limits, or a deductible you'll hate later.
These are good instincts because they focus on fit, not just price.
Advice that needs context
A lot of Reddit comments flatten complex decisions into slogans.
Take “always choose the highest deductible.” That can reduce premium, but it only works if you can comfortably absorb that out-of-pocket amount during a bad month. A deductible should match your cash reserves, not your optimism.
The same goes for “just bundle everything.” Bundling auto insurance or car insurance with renters insurance can be useful, and sometimes it also fits with broader household planning around home insurance and life insurance. But a bundle isn't automatically the best deal if one line is overpriced or if the bundled renters form has important exclusions for your area.
Cheap is only good when the policy still works the way you think it works.
Red flags renters should catch early
These are the ones I'd take seriously before you click buy.
- A landlord or property manager won't explain the insurance requirement clearly. They can require coverage, but you still need to know the minimums and any additional insured or interested party request.
- The quote process avoids specifics. If nobody will answer direct questions about covered property, liability, exclusions, or loss-of-use terms, that's a bad sign.
- You're pushed toward one insurer without comparison. Convenience isn't the same as value.
- You assume brand reputation solves everything. Big names can be fine. So can digital-first carriers. The real question is whether that policy form fits your California risk profile.
The insurer-name debate on Reddit
Threads often ask whether Lemonade, GEICO, State Farm, Progressive, or Farmers is “best.” That's the wrong framing. A better question is: who is competitive for your ZIP code, your building type, your bundling setup, and your coverage needs?
The winning carrier on Reddit might be wrong for your block, your lease, or your wildfire exposure. That's why anecdotal advice should start your research, not finish it.
How to Find the Best California Renters Insurance Rate
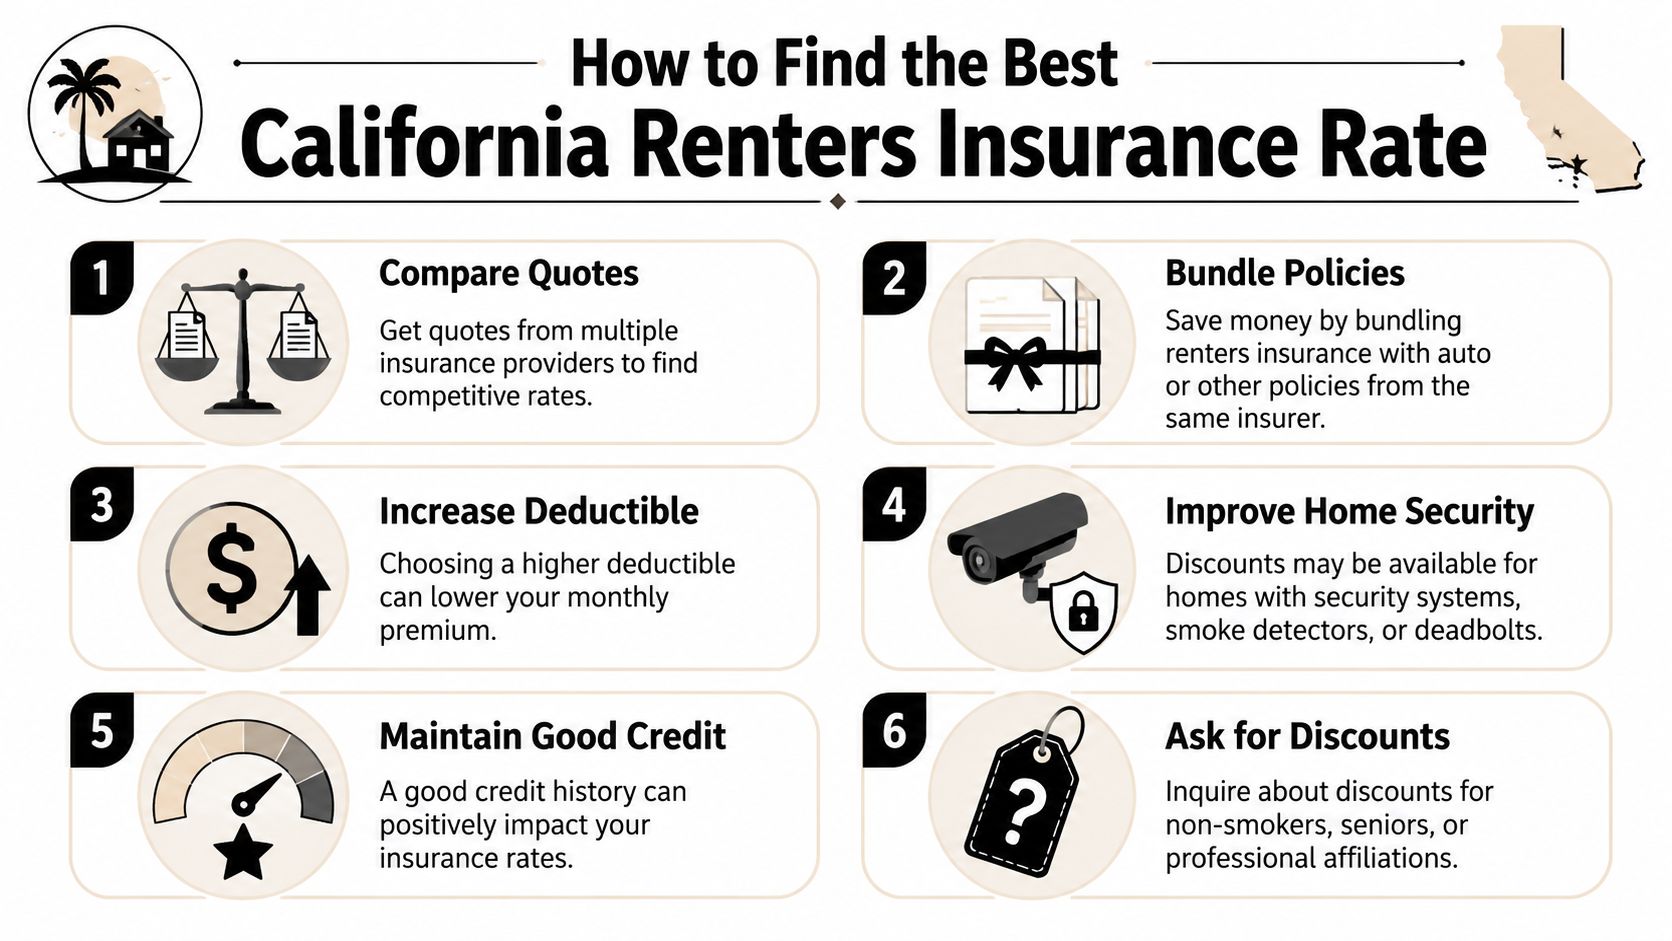
If you want a better renters rate in California, don't treat the premium like a mystery number handed down from above. You have levers. Some affect price directly. Others affect whether the quote is worth buying.
California pricing also varies by location. NerdWallet reports an average annual renters premium of $155 in California, with Los Angeles at $191 per year, San Francisco at $164, and San Diego at $142, which shows how local risk shapes cost in different cities, as detailed in NerdWallet's published California rate comparison.
The levers that usually matter most
Start with the variables you can control.
- Compare quotes side by side. Don't compare only premium. Compare deductible, property limit, liability limit, and whether the form fits your risk area.
- Bundle strategically. If the same insurer handles your renters insurance and auto insurance or car insurance well, bundling can simplify billing and sometimes improve value.
- Choose a deductible on purpose. Lower premium sounds nice until you realize the out-of-pocket amount is unrealistic for your budget.
- Ask about protective-device discounts. Smoke detectors, deadbolts, and similar features can matter with some carriers.
- Review the policy type, not just the logo. The right insurer on paper is still wrong if the coverage is thin.
What doesn't work
Many renters waste time chasing tiny cosmetic differences between quotes while ignoring the key drivers.
A flashy app doesn't make a policy stronger. A low price doesn't mean the same protections are included. A quote that arrives fast isn't automatically a better quote. And if you're in a tougher underwriting area, trying to force-fit a bargain policy can backfire.
A simple quote review checklist
Use this when comparing options:
| Question | What you want |
|---|---|
| Does it meet the lease requirement? | No last-minute rewrite after purchase |
| Are property and liability limits clear? | No guessing about what's actually covered |
| Are California-specific exclusions explained? | No surprises tied to wildfire or earthquake issues |
| Is the deductible realistic for me? | A number you could actually pay |
| Would bundling help my broader insurance setup? | Practical fit with auto, home, or life insurance planning |
A renter who compares coverage this way usually makes a better decision than the renter who just hunts for the lowest monthly number.
Your Simple Next Steps to Get Covered
If you've read a pile of Reddit threads and still feel stuck, use a short checklist instead of opening more tabs.
Step one, value your stuff quickly
Walk through your place with your phone. Record each room. Open closets and drawers. Make a basic list of electronics, furniture, kitchen gear, clothing, and anything expensive enough to hurt if you had to replace it tomorrow.
You do not need a perfect spreadsheet. You need a realistic estimate.
Step two, read the lease before shopping
Check what the landlord requires. Some leases specify minimum liability coverage, proof-of-insurance timing, or how the landlord should be listed on the policy. Don't assume. Verify.
A lot of renters create extra work for themselves when they buy a policy first and read the lease later.
Step three, get real quotes and ask real questions
Use your inventory, your lease, and your ZIP code to compare options. Ask about deductibles, exclusions, wildfire concerns, and whether any earthquake option applies to your belongings.
A fast way to move from research to action is requesting a California insurance quote online. That gives you a baseline you can evaluate instead of relying on random Reddit screenshots and old comment threads.
The best renters policy is the one you understand before the claim, not after it.
California Renters Insurance FAQs
Does my renters insurance cover my roommate's belongings too
Usually, don't assume it does. Roommate situations create confusion because people share a space but not always a policy interest. The safest move is for each roommate to carry their own coverage unless the insurer clearly confirms otherwise in writing.
That avoids claim disputes about ownership, limits, and who is insured.
What happens if my dog bites a guest in my apartment
This can become a liability claim, but the exact outcome depends on the policy terms and any animal-related restrictions. Some policies handle this better than others, and some carriers are stricter about certain situations.
Don't rely on a generic “pets are fine” answer. Ask directly how liability applies and whether any exclusions affect your household.
How does the claims process work if my laptop is stolen
Start by documenting what happened, notifying the relevant parties if needed, and gathering proof that you owned the item. That could include receipts, photos, serial information, or your room-by-room video inventory.
Then file the claim with the insurer and be specific. Claims go more smoothly when the renter can show what was lost, where it was, and when it happened.
Does renters insurance cover items stolen from my car
Sometimes the item may fall under your renters policy if it's your personal property, but the vehicle itself is a separate insurance issue handled through auto insurance or car insurance. That split confuses a lot of people.
The key point is to separate where the item was from what policy covers the vehicle. Ask how off-premises personal property is treated under your renters form.
Is renters insurance required in California
California state law doesn't require it, but landlords can require it through the lease. So in practice, many renters do need it to move in or stay compliant with the rental agreement.
Legal requirement and lease requirement are not the same thing.
Should I bundle renters insurance with auto or life insurance
Sometimes yes, sometimes no. Bundling can simplify things and may help the overall price, especially if you already carry auto insurance or are reviewing multiple lines like home insurance and life insurance. But never let the bundle distract you from checking exclusions, deductibles, and actual fit.
A clean insurance setup is better than a crowded one.
If you want help sorting through quotes without the Reddit noise, Mai & Associates is a practical place to start. They work with California renters, drivers, and homeowners across the state, and they can help compare renters insurance alongside auto insurance, car insurance, home insurance, and life insurance needs. That's especially useful if you need guidance on wildfire exposure, earthquake options, lease requirements, or bundling choices and want answers from licensed California agents instead of comment threads.