Unlocking Your Multi Car Insurance Discount in California
If you’ve got more than one car in your driveway, a multi-car insurance discount is one of the easiest ways to save on your California insurance. Think of it as a bulk discount from your insurance company. By putting two or more vehicles on a single car insurance policy, you can often cut your premium by 10% to 25%.
Insurance companies love this arrangement because it reduces their own administrative costs, and they’re happy to pass a chunk of those savings directly on to you.
Understanding the Multi-Car Insurance Discount
It’s a simple concept, really. Imagine going to the grocery store. You can buy one can of soup at a time, but grabbing the value pack almost always costs less per can. Multi-car insurance operates on that exact same logic.
Instead of juggling separate policies for each car—each with its own billing cycle, renewal date, and stack of paperwork—you roll them all into one convenient plan. It’s a win-win. You get a lower premium and less hassle, while your insurer gets less paperwork and a loyal customer they're more likely to keep for the long haul.
Why This Discount Matters in California
Let's be honest, auto insurance in California isn't cheap. Rates here often run higher than the national average, so every discount counts. The multi-car discount isn’t just a small perk; it’s a core savings strategy for couples, families, or anyone with multiple vehicles at the same address.
The core benefit is straightforward: one policy, one payment, and one renewal date for all your vehicles. This convenience, combined with substantial savings, makes it a popular choice for California drivers.
Consolidating your auto policies does more than just save you money—it streamlines your financial life. It also builds a stronger relationship with your insurer, which can open the door to other benefits down the road. This is often the first and most impactful step toward bundling other policies, like home insurance or renters insurance, for even bigger savings.
To learn more about other ways to save, feel free to check out our other insurance guides. But if you're looking for an immediate impact, combining your vehicles is the perfect place to start.
How Multi-Car Discounts Work for California Drivers
At its heart, a multi-car insurance discount is a simple thank-you from your insurance company for making their life easier. Think about it from their perspective: managing one household policy with three cars is much more efficient than juggling three separate policies, each with its own paperwork, billing cycle, and renewal date.
This administrative saving on their end gets passed directly to you. Instead of dealing with a pile of mail and multiple due dates, you get one streamlined policy. It's a win-win, rewarding your loyalty and organization with a lower premium.
Common Eligibility Rules in the Golden State
So, how do you get in on this? While the fine print can differ from one carrier to the next, the basic requirements for a multi-car discount in California are pretty consistent.
The big one is that all vehicles on the policy must be garaged at the same primary address. This proves to the insurer that they're all part of the same household. The cars also need to be registered to family members living at that address—think spouses, partners, or your kids.
Here’s a quick rundown of the usual criteria:
- Shared Residence: All cars must be parked overnight at the same California address.
- Family Relationship: The policyholders usually need to be related (by blood, marriage, or domestic partnership) and live together.
- Vehicle Ownership: The cars are typically registered to the people named on the policy.
A Real-World Glendale Family Scenario
Let's make this real. Picture a family in Glendale. Mom and Dad each have a car for their commute, and they just added their teenager to the policy with an older, safer sedan for him to drive.
Instead of getting hit with the astronomical cost of a standalone policy for their new driver, they add his car to their existing one. Because all three cars are parked at their Glendale home and registered to family members, they easily qualify for the multi-car discount. This single move not only simplifies their bill-paying but also takes a significant bite out of the high cost of insuring a teen.
In California's notoriously expensive insurance market, a multi-car discount is a powerful tool. It directly lowers the cost of key coverages like liability, collision, and comprehensive, meaning you save money across the board.
For California families, bundling cars can be a total game-changer. Just think about navigating the freeways around Glendale or Escondido—insuring each of those cars separately can really hurt the budget. Combining them can often knock 10% to 25% off the most expensive parts of your policy.
Top-tier carriers we work with at Mai & Associates, like GEICO, offer discounts of up to 25%, while State Farm is right behind them with up to 20%. It’s one of the most common and effective ways to save. You can learn more about how this and other discounts are applied to your auto insurance in California policy.
How to Maximize Your Savings on a Multi-Car Policy
Getting a multi-car discount is a fantastic start, but it's really just the first step. To get the absolute best deal, you need to think a bit more strategically about how your entire California insurance portfolio is structured. It’s about more than just adding cars to a list; it’s about finding every possible way to stack your savings.
A great place to begin is by aligning the coverage limits across all your vehicles. While you can definitely tweak the protection for each car, keeping your liability limits consistent creates a solid, uniform financial safety net for your whole family. This simple act of consistency often makes your policy more appealing to insurance carriers, which can lead to better rates.
This flowchart breaks down the typical eligibility path for a multi-car discount.
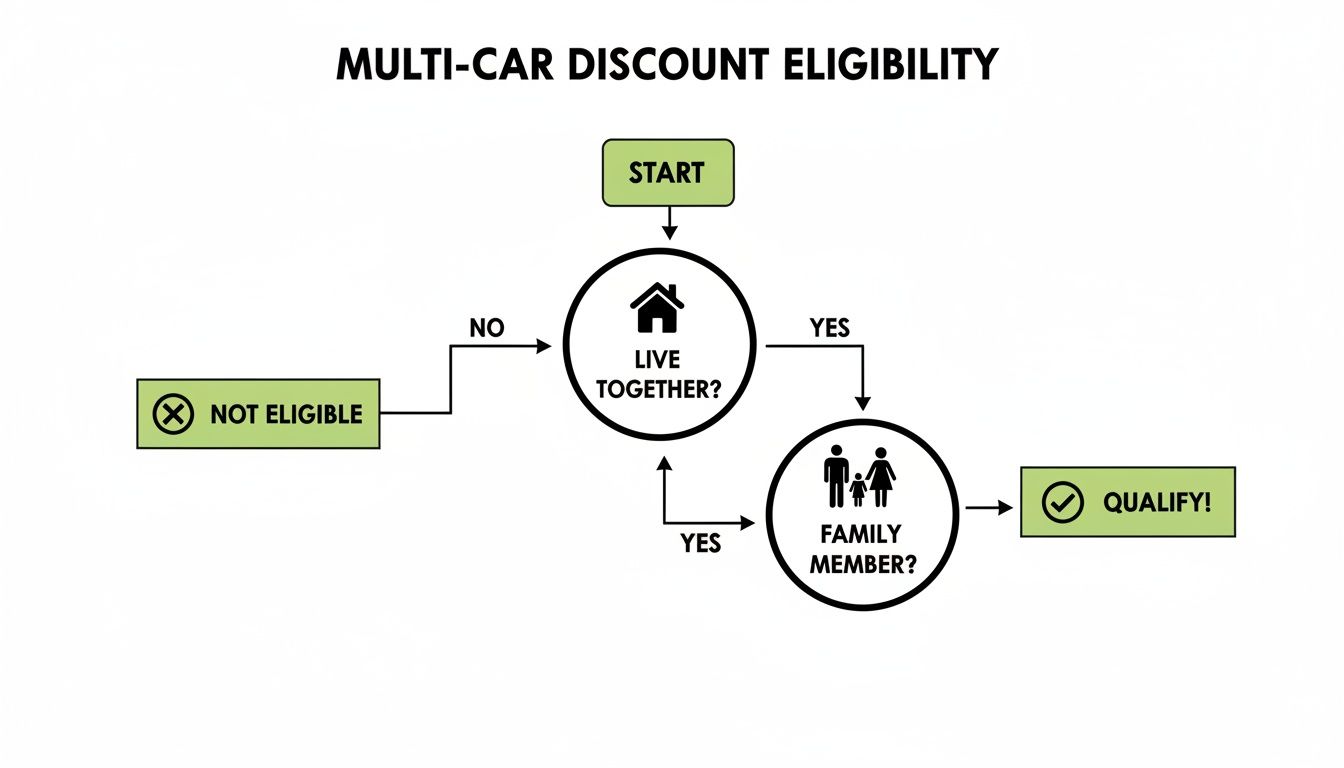
As you can see, the main requirements usually boil down to sharing an address and being related, which makes this a pretty straightforward discount for most California households.
Stacking Discounts for the Biggest Impact
Think of your multi-car discount as the base of your savings. The real magic happens when you start "stacking" other available discounts right on top of it. Insurance companies have a whole menu of ways to save, and combining them is how you’ll see a serious drop in your premium.
Here are a few of the most powerful discounts you can stack with a multi-car policy:
- Multi-Policy Discount: This is the big one. When you bundle your auto insurance with your home insurance, renters insurance, or even a life insurance policy, you unlock one of the most substantial discounts an insurer offers—often saving you 20% or more.
- Good Student Discount: Got a young driver on your policy? If they keep a "B" average or higher in school, this discount can take a big bite out of the higher premiums that typically come with insuring a teen.
- Telematics Programs: Many carriers now offer programs that reward you for safe driving. By using a simple smartphone app or a small plug-in device that tracks your driving habits, you can earn significant reductions on your premium just for being a safe driver.
Combining these discounts creates a multiplier effect. A multi-car policy might save you 15%, but when you add a home and auto bundle plus a good student discount, your total savings could climb much, much higher.
What About High-Risk Drivers?
But what if one person in the household has a spotty driving record? It’s a common concern. Adding a driver with a history of accidents or tickets can sometimes cause the premium to jump so high that it completely wipes out the multi-car discount.
In those specific situations, it might actually be cheaper to insure the high-risk driver on their own separate policy. You'd miss out on the multi-car savings for that vehicle, but you’d also isolate their higher risk from the rest of the family's policy, which could save you more money overall. The only way to know for sure is to run the numbers and get quotes for both scenarios.
Remember to look for other opportunities to save, too. Things like installing a car alarm or having other anti-theft features on your vehicles can also chip away at your premium. Every little discount adds up, turning a good deal into a great one.
Multi-Car Discount vs. Bundling Home and Auto
It's really easy to get insurance terms mixed up, but telling the difference between a multi-car discount and a bundling discount is the secret to getting the best possible rate. They're both fantastic ways to save money, but they work in completely different ways.
Think of it like this: a multi-car discount is a loyalty reward. Your insurance company is essentially saying, "Thanks for bringing all your cars to us," and gives you a price break for keeping things simple under one auto insurance policy.
On the other hand, bundling—which you’ll often hear called a multi-policy discount—is a much bigger-picture strategy. This is where you bring completely different types of insurance policies together with one carrier, like pairing your car insurance with your home insurance in California, renters insurance, or even a life insurance policy.
Key Differences at a Glance
The easiest way to really see how these two work is to put them side-by-side. Each discount has its own purpose, its own rules for who qualifies, and offers different savings potentials. While both are incredibly valuable for California drivers, knowing which one to use—and when—is what really matters.
Let's break down the main distinctions in a clear way.
Multi Car vs Multi Policy Discount Breakdown
This table gives you a clear comparison between the two most popular California insurance discounts, helping you figure out which savings strategy is the right fit for your situation.
| Feature | Multi Car Discount | Multi Policy (Bundling) Discount |
|---|---|---|
| What It Covers | Two or more vehicles (cars, trucks, etc.) under a single auto policy. | Different types of policies (e.g., auto + home, auto + renters) with the same insurer. |
| Primary Goal | To simplify auto insurance management and reward you for insuring multiple cars. | To build a broader relationship with your insurer by protecting more of your assets. |
| Typical Savings | Usually between 10% and 25% off your auto insurance premium. | Often provides a higher percentage discount, potentially 20% or more, on both policies. |
| Who It's For | Households with more than one vehicle parked at the same address. | Anyone who needs more than one type of California insurance, like a driver who also owns a home. |
As you can see, one is focused purely on your vehicles, while the other is about protecting your wider world of assets.
The Power of Combining Both Discounts
Now, here's the most important thing to remember: you don't have to choose just one. In nearly every case, the absolute biggest savings come from combining a multi-car discount with a multi-policy discount. This is the real expert-level move for cutting your insurance costs in California.
By placing your multiple vehicles and your home under the same insurance company, you stack two of the most significant discounts available. This creates a powerful, cost-effective safety net that protects your family's biggest assets, from your car to your home.
Let's imagine a family in Costa Mesa with two cars and a home. They could get a 15% multi-car discount for their vehicles, and then layer a 20% multi-policy discount on top of that for both their home and auto insurance policies. This stacking strategy can easily add up to hundreds of dollars in savings every single year.
Why Comparing Quotes Is a Non-Negotiable Step
It’s easy to assume your current insurance company is giving you the best deal, especially if you’re already getting a multi-car discount. But in California's competitive market, that kind of brand loyalty can be a very expensive mistake. Shopping around isn’t just a good idea—it’s an essential step to make sure you aren't leaving money on the table for your California insurance.
While just about every insurer in California offers a multi-car discount, the actual savings can swing wildly from one company to the next. One carrier might knock off a modest 8%, while another could offer a generous 25% for the very same cars and drivers. That difference alone can easily add up to hundreds of dollars a year.
Why the Same Cars Get Different Prices
So, how can that be? Every insurance company has its own secret sauce for calculating premiums. They all look at the same things—driving records, vehicle types, your ZIP code—but they weigh each factor differently. This is why two top-rated companies can look at the exact same family and come back with completely different numbers.
Let’s put this into a real-world scenario.
Picture a family in Escondido with two common vehicles, a Honda CR-V and a Toyota Camry, both driven by adults with clean records.
- Insurer A might give them a 12% multi-car discount, landing them with an annual car insurance premium of $2,100.
- Insurer B, on the other hand, might offer a bigger discount of 20% and have better base rates for their situation, bringing the premium down to $1,750.
That’s a $350 difference for the same coverage. Without comparing quotes, this family would have no idea they were overpaying.
The Advantage of an Independent Agency
This is exactly where working with an independent agency makes all the difference. Instead of being stuck with the rates from a single company, you get a clear, side-by-side comparison of quotes from multiple top-rated insurers. It takes all the guesswork out of the equation for all your California insurance needs.
The global multi-car insurance market is thriving, which just goes to show how effective this strategy is for families. In the U.S., you'll see big names like State Farm, Allstate, and Progressive, but their pricing is all over the map. Bundling your cars doesn't just cut costs—often by 10-25%—it also simplifies managing your policies, which is a huge help when you're also reviewing options like home insurance or even California Fair Plan policies. You can find more details about these multi-car insurance market trends on htfmarketintelligence.com.
An independent agent works for you, not for one insurance company. Their goal is to find you the best combination of price and coverage, whether it's for auto insurance, home insurance, or life insurance.
By putting several offers head-to-head, you can pick a policy based on hard numbers, not just old habits. It’s the only way to be sure your multi car insurance discount is actually giving you the maximum savings possible.
Ready to See Your Multi-Car Savings? Let's Get Started.
You now have a solid understanding of how a multi-car insurance discount works—think of it as a bulk discount, but for protecting your family's vehicles. We've walked through the ins and outs for California drivers, from who qualifies to how you can stack this discount with others (like bundling your home insurance) to really drive down your premium.
The next step is to move from theory to reality. It's time to find out exactly what those savings could look like for you.
The advantages are pretty compelling. Consolidating your cars onto one policy not only unlocks significant savings but also makes your life a whole lot easier. Imagine one bill, one renewal date, and a single point of contact for all your vehicles. It’s about more than just saving money; it’s about simplifying your financial life.
Your Personalized Quote is Just a Click Away
Finding out what you could save is simpler than you might think. Our licensed agents at Mai & Associates are on standby to do the heavy lifting for you. We'll shop around with our network of top-rated insurance carriers to find the perfect blend of coverage and cost for your specific needs.
Here’s what you can expect when you work with us:
- Same-Day Quotes: No waiting around for days. We'll get you a clear, no-obligation quote quickly so you can make a smart decision right away.
- Multilingual Support: We believe clear communication is key. Our team is fluent in English, Spanish, Armenian, Russian, and Vietnamese to make sure you're comfortable and confident in your choices.
- Real Expertise: We're not just about cars. We specialize in all types of California insurance, from auto and home to renters and life insurance, so we can help you see the big picture.
Stop wondering if you're overpaying. Take the next step today and get a personalized insurance quote to see how much a multi-car policy can lower your rate. It’s the easiest way to protect what matters most while keeping more money in your pocket.
Your Top Questions About Multi Car Discounts, Answered
Even when you know the basics, the little details can trip you up. Let's tackle some of the most common questions California drivers ask when they're thinking about bundling their cars onto one policy. This should clear things up and help you feel confident about making the move.
Do All My Cars Need the Same Exact Coverage?
Nope, not at all! This is a big myth, but the truth is, insurance companies are pretty flexible. You get to customize the coverage for each car on your policy to fit its specific needs.
Think about it this way: you’d probably want the full works—comprehensive and collision—on your new SUV that still has a loan on it. But for that trusty old sedan you've paid off and just use for errands? You might be perfectly fine with just the state-required liability coverage. This approach lets you get the multi car insurance discount without overpaying for protection you don't need on every vehicle.
Can I Add My Roommate's Car to My Policy?
This is where things get a bit gray, and it really depends on the insurance company. Generally, multi-car policies are designed for family members who live together, with all the cars registered at the same address. Adding a roommate isn't impossible, but it’s definitely not standard.
Being upfront and honest with your insurance agent is crucial here. You need to tell them exactly who lives with you and who's driving each car. Hiding these details could lead to a denied claim when you need coverage the most.
What Happens to the Discount if I Sell One of My Cars?
If selling a car drops you down to just one vehicle on the policy, then yes, you'll lose the multi car discount when your policy renews. Your premium will be recalculated based on the standard rate for a single car.
But don't worry if you're just swapping out one car for another. Most insurers give you a grace period, usually a few weeks, to add the new car to your policy and keep your discount going without a hitch. The trick is to call your agent right away so they can handle the transition smoothly for you.
Is It Always Cheaper to Bundle Two Cars?
In well over 95% of situations, absolutely. The savings are almost always there. The rare exception is when one driver in the household is considered extremely high-risk—think someone with several recent accidents or a DUI on their record.
In that specific scenario, adding them to the same policy as a driver with a squeaky-clean record could cause the rate to skyrocket, potentially canceling out any discount. The only way to know for sure is to compare quotes side-by-side: one for a combined policy and two for separate ones. An independent agent can be a huge help here by running both numbers for you.
Ready to stop wondering and start saving? The team at Mai & Associates can provide a free, no-obligation comparison of your options for auto, home, renters, and life insurance. Discover your potential savings today.