Guaranteed Life Insurance in California: A Clear Guide
When you hear the term guaranteed life insurance, think of it as a type of whole life insurance policy that you can't be turned down for, provided you're within the right age bracket. It's a straightforward financial safety net that completely skips the medical exams and health questions, opening a door for folks who might not qualify for other coverage because of their health history.
A Financial Safety Net for Every Californian
Picture an insurance policy designed with one simple goal: acceptance. For many Californians—from seniors in Glendale planning for funeral costs to someone in Escondido wanting to settle final debts—traditional life insurance can feel like an impossible hurdle due to a complicated health history. This is exactly where guaranteed life insurance comes in, offering a crucial piece of the puzzle alongside other protections like California auto insurance and home insurance.
It’s essentially an automatic pass. Instead of scrutinizing your medical records, these policies focus almost entirely on your age. If you fall within the eligible range, which is usually between 50 and 85, you’re almost certain to be approved. This accessibility solves a huge problem for many families, making sure their loved ones aren't blindsided by unexpected expenses.
Who Benefits Most from This Coverage
Now, this type of policy isn't a one-size-fits-all solution, but for the right person, it's perfect. It offers a practical way to handle specific financial responsibilities without the headache of a long, invasive application process.
The people who get the most out of it often include:
- Individuals with pre-existing health conditions who've been denied other kinds of life insurance.
- Seniors looking to set aside funds specifically for burial costs, cremation services, or other final expenses.
- Anyone needing a smaller policy to cover things like outstanding medical bills, credit card debts, or personal loans.
- Californians who simply want to leave a small inheritance or a gift to a favorite charity.
The whole point is to give you peace of mind. By locking in a guaranteed policy, you ensure money will be there when your family needs it most, shielding them from financial stress during an already difficult time. If you run into any unfamiliar terms, you can review key insurance concepts in our comprehensive glossary.
The idea of providing a guaranteed payout isn't new—it actually has roots going all the way back to 1762. Its legacy of reliability continues today as a key piece of financial planning for millions of families.
The Growing Need for Secure Coverage
More and more people are realizing just how important life insurance is. The concept of a guaranteed payout first took hold with the Equitable Life Assurance Society in London way back in 1762. That same principle of reliability is why industry forecasts predict that U.S. individual life insurance premiums will grow by 2% to 6% in the coming years.
This trend is driven by a growing awareness of a major coverage gap—over 100 million U.S. adults admit they need more life insurance, but only about half of them actually have a policy. For families here in California, guaranteed policies offer real stability with fixed premiums that never change and death benefits that are locked in.
Let's break down the core features with a quick summary.
Guaranteed Life Insurance at a Glance
This table provides a snapshot of what makes guaranteed issue life insurance a distinct and valuable option for many people.
| Feature | Description |
|---|---|
| No Medical Exam | Approval does not require a physical exam or any medical tests. |
| No Health Questions | You won't be asked to fill out a detailed questionnaire about your health history. |
| Guaranteed Approval | Acceptance is virtually certain as long as you meet the specific age requirements (e.g., 50-85). |
| Coverage Amount | Policies are typically for smaller amounts, usually $5,000 to $25,000, for final expenses. |
| Graded Death Benefit | The full payout is only available after a waiting period, typically the first two years of the policy. |
| Fixed Premiums | Your monthly payment is locked in and will never increase as long as you keep the policy. |
Ultimately, this type of coverage is all about providing a reliable, no-fuss solution for a very specific need.
At Mai & Associates, we know the unique financial landscape in California, from the ins and outs of home insurance and auto insurance to the absolute necessity of life insurance. We’re here to help you navigate these important decisions and find the right protection to secure your family’s future.
How the Graded Death Benefit Period Actually Works
If there’s one thing to understand about guaranteed life insurance, it’s the graded death benefit. It can sound a bit technical, but it’s really just a temporary waiting period—usually the first two or three years of the policy.
Think of it like this: for the first couple of years, the policy isn't fully "matured" for every situation. This waiting period is the key reason insurers can offer coverage without a medical exam or asking a single health question. It’s a trade-off for guaranteed acceptance.
Natural Causes Versus Accidental Death
During that initial graded period, what your family receives depends entirely on how you pass away. This is where the distinction between natural and accidental death becomes critical.
If death is due to a natural cause, like an illness or simply old age, within those first two or three years, your beneficiaries won’t get the full death benefit. Instead, the insurance company refunds all the premiums you paid in, usually with a bit of interest on top—often around 10%.
But if the death is from a covered accident, the story is completely different. A car insurance policy might cover vehicle damages, but it's life insurance that protects your family financially. A car crash, a slip and fall, or another qualifying accident means the full policy amount is paid out. This is true even if the accident happens just one day after the policy starts, providing immediate protection against the unexpected.
This decision tree helps visualize the basic qualification path.
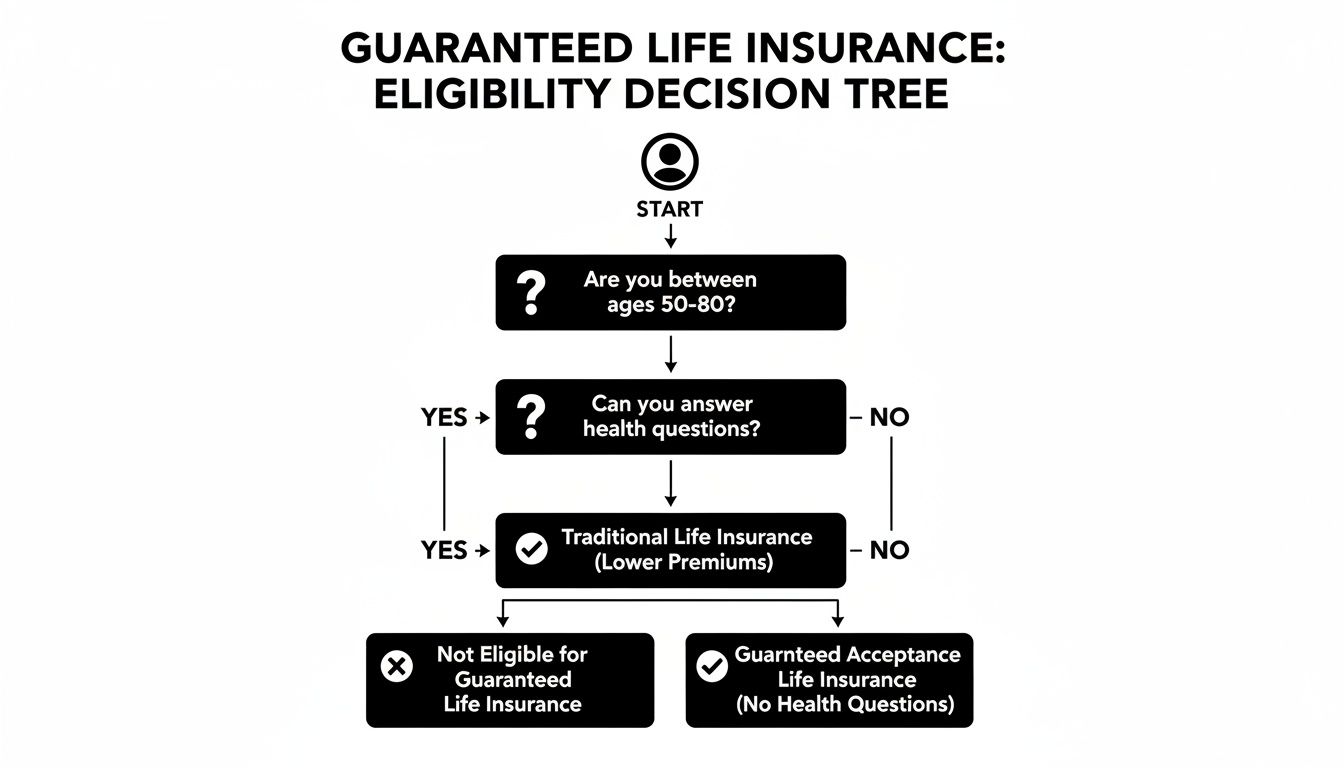
As you can see, eligibility for guaranteed life insurance really comes down to your age, allowing you to skip the health questions that are standard for traditional plans.
A Practical California Example
Let’s make this real. Imagine Maria, a 68-year-old from Escondido, takes out a $15,000 guaranteed issue policy to make sure her final expenses are covered. Her policy has a two-year graded death benefit.
Here’s how that could play out:
- Scenario 1 (Natural Causes): Maria sadly passes away from a heart condition 18 months after her policy began. Since her death was due to natural causes and happened during the graded period, her family won't get the full $15,000. They will, however, get back every dollar she paid in premiums, plus interest.
- Scenario 2 (Accidental Death): Now, let's say Maria was in a car accident on the freeway and passed away from her injuries only six months into the policy. In this case, her beneficiaries would receive the full $15,000 payout. The accidental death coverage kicks in right away, bypassing the waiting period.
This two-part structure is how insurers can manage their risk while still offering a vital safety net for people who need it most.
The graded death benefit is the engine that makes "no questions asked" insurance possible. It protects the insurance company from immediate high-risk claims while ensuring the policy is there for its intended purpose—covering final expenses down the road.
Getting a handle on this waiting period is crucial. If you're curious about how these kinds of limitations work in other types of California insurance, you can learn more about general insurance waiting periods. This provides some good context for how the industry operates.
Once this initial two or three-year period is over, the policy is in full force. From that point on, the full death benefit gets paid out for any cause of death, giving you and your family complete peace of mind.
Weighing the Pros and Cons for Your Situation
Alright, let's have a frank discussion about guaranteed life insurance. Like any tool in the financial shed, it's perfect for some jobs but not the right fit for others. Understanding both sides of the coin is the only way to know if it truly makes sense for your family, whether you're in Westlake Village or down in Costa Mesa.
The biggest "pro" is powerful and simple: guaranteed acceptance. For so many Californians who've been turned down for traditional life insurance because of their health history, this is more than just a feature—it’s a lifeline. It completely removes the hurdles of medical exams and invasive health questions, offering a clear path to getting covered.
That certainty brings a tremendous amount of peace of mind. You can apply knowing that as long as you fall within the age bracket—usually between 50 and 85—you will be approved. It's a straightforward promise of protection when you need it most.
The Clear Advantages of Guaranteed Acceptance
The benefits aren't just about getting a "yes." The whole process is built for speed and simplicity, sidestepping the weeks, or even months, of waiting that can come with a fully underwritten policy.
Here’s what makes it such an appealing option for many:
- No Medical Exam Required: You can forget about scheduling doctor visits, giving blood samples, or having your medical records pulled.
- No Health Questions Asked: Your health history, no matter how complicated, won't stand in the way of you qualifying.
- Fast and Simple Application: The application is incredibly direct and can often be completed in just a few minutes.
- Fixed Premiums for Life: Once your policy is in place, your monthly payment is locked in forever, which makes it incredibly easy to budget around.
However, this easy access comes with some important trade-offs. The "cons" are a direct result of the insurance company taking on a risk without knowing the full picture of an applicant's health. You absolutely need to consider these downsides before signing on the dotted line.
The most noticeable drawbacks are the higher premiums for the amount of coverage you get and the much smaller death benefits. You will simply pay more per dollar of coverage than you would with a traditional policy, and the benefit amount usually caps out between $5,000 and $25,000. And, as we covered earlier, the graded death benefit means the full payout for natural causes is delayed for the first two or three years.
Understanding the Financial Trade-Offs
It’s really important to weigh these factors carefully. This type of policy is designed for a very specific purpose: covering final expenses like a funeral, cremation, or small outstanding debts. It was never intended for bigger financial goals like replacing a lifetime of income or paying off a mortgage, which are better suited for other types of California life insurance.
To make these policies work, insurers use smart financial strategies behind the scenes. For instance, in a single year, U.S. insurers utilized over $100 billion in reinsurance deals to manage their long-term obligations, ensuring they can always pay out claims. This is one reason why guaranteed whole life plans have a historical lapse rate under 4%, a stark contrast to the 20% rate for term life. This financial stability, which you can read more about at S&P Global, adds another layer of security for California policyholders.
For the right person, guaranteed life insurance isn’t just a policy—it’s a solution. It provides a dignified way to ensure final expenses are handled without burdening family, especially when other insurance options are off the table.
Deciding if this is the right path means looking at your entire situation. For a Californian with significant health issues who just needs to secure funds for their funeral, the higher cost is a worthwhile price for guaranteed peace of mind. But if you’re healthy, other types of insurance will almost certainly offer more coverage for a lower price.
To really see how these policies stack up, let’s look at a side-by-side comparison.
Comparing Guaranteed Issue vs Other Life Insurance Types
Choosing the right policy in California can feel overwhelming, but breaking it down by key features makes it much clearer. The table below compares the three main types of life insurance to help you see where guaranteed issue fits in.
| Feature | Guaranteed Issue | Simplified Issue | Fully Underwritten Term |
|---|---|---|---|
| Medical Exam | No | No | Yes |
| Health Questions | No | Yes (a few) | Yes (in-depth) |
| Approval Speed | Instant or within days | Days to weeks | Weeks to months |
| Coverage Amount | Low (e.g., up to $25,000) | Moderate (e.g., up to $500,000) | High (often $1 million+) |
| Typical Premiums | Highest | Moderate | Lowest |
| Graded Death Benefit | Yes (usually 2-3 years) | Sometimes | No |
As you can see, guaranteed issue life insurance serves a very specific need. It's unmatched in accessibility but is more limited in coverage and less cost-effective than other options that require some level of health vetting.
What Are Your Other Life Insurance Alternatives?
While guaranteed issue life insurance is a fantastic safety net for many, it’s not the only way to secure your family's future. It's smart to look at all your options to make sure you're getting the most coverage for your money. Think of it like buying car insurance—a basic liability policy is essential, but you might want comprehensive coverage for a brand-new vehicle.
Guaranteed issue policies are like that reliable sedan: easy to get, perfect for a specific need like covering final expenses, but with some limits. If you're in decent health, you might qualify for a policy that gives you more horsepower for your dollar. Let's explore the other models on the lot.
Simplified Issue Life Insurance: The Middle Ground
If guaranteed issue is the "no questions asked" policy, then simplified issue life insurance is the "just a few questions" alternative. It’s a great middle-of-the-road option for a lot of folks in California. You still get to skip the medical exam, which is a huge plus, but you will have to answer a short health questionnaire.
The questions are usually pretty basic, like:
- Have you been diagnosed with a terminal illness?
- Are you currently living in a hospital or nursing home?
- Have you tested positive for HIV or AIDS?
Because the insurance company gets a little peek into your health history, they're taking on less of a gamble. That translates directly into savings and better coverage for you: lower premiums and higher death benefits than you'd find with a guaranteed issue plan. This is an excellent choice if you might not get approved for a fully underwritten policy but are healthy enough to clear a basic health screening.
Fully Underwritten Policies: The Most Affordable Option
For those in good health, nothing beats the value of a traditional, fully underwritten life insurance policy. This process is the most detailed, involving a full health questionnaire and a free medical exam. Yes, it takes more time and effort, but the payoff is huge.
By getting a complete picture of your health, insurers can offer their absolute lowest prices for very high coverage amounts, often reaching $1 million or more. If your goal is to replace lost income, pay off a mortgage, or make sure your kids can go to college, a fully underwritten term or whole life policy is almost always the most cost-effective way to do it. You can dive deeper into this by checking out our guide on life insurance options in California.
The insurance world is always evolving to fit people's real-life needs. We're seeing a clear trend toward making the application process smoother without sacrificing quality.
The global life insurance market is booming, with total premiums projected to reach $4.8 trillion by 2035. This surge is partly because the pandemic highlighted a major coverage gap for an estimated 100 million Americans. As a result, products like simplified issue final expense plans are seeing double-digit sales growth, proving that people want accessible options that are a step up from guaranteed issue.
Other Permanent Life Insurance Choices
Beyond term life, the world of permanent insurance has a few other flavors. When you're looking at alternatives, you might come across options like Variable Universal Life Insurance (VUL), which bundles a death benefit with an investment account. These products are more complex and carry some market risk, but they offer a ton of flexibility and can be a powerful tool for certain financial strategies.
At the end of the day, picking the right policy is all about matching the product to your health, your budget, and your goals. Whether you need the absolute certainty of guaranteed issue, the balanced approach of simplified issue, or the rock-bottom prices of a fully underwritten plan, there's an option out there for you. The key is to weigh them carefully to find the best possible protection for your family.
A Closer Look at California's Insurance Rules
When you're shopping for any type of California insurance, you're not going it alone. The state has a robust set of rules in place, overseen by the California Department of Insurance (CDI), all designed to protect you. These regulations make sure the entire process, from getting a quote to filing a claim, is fair and transparent.
One of the best consumer protections you have is the “free look” period. It’s a state-mandated safety net. After your policy is delivered, you get a set window of time—usually between 10 and 30 days—to review every last detail. If you decide it's not the right fit for any reason at all, you can cancel and get a full refund of every penny you've paid. No hassle, no penalties.
The California Free Look Period: Your Safety Net
Think of the free look period as a test drive. It's your chance to take the policy home, kick the tires, and make absolutely sure it's what you want and need.
This is your time to double-check everything:
- Is the death benefit amount exactly what you agreed to?
- Are the premium payments manageable for your budget?
- Do you fully grasp how the graded death benefit and waiting period work?
If something feels off, or if you just have a change of heart, you can walk away clean. This rule gives you the power to make your final decision with complete confidence, knowing you had a chance to back out.
Factoring in California's High Cost of Living
Planning for final expenses in California means dealing with a different reality. The cost of just about everything is higher here, and that includes funerals, legal fees, and all the other expenses that come up at the end of life. A funeral that might cost $10,000 elsewhere in the U.S. could easily run $12,000 or more in a California city.
Having a dedicated life insurance policy isn’t just about covering bills. It’s about giving your family immediate access to cash when they need it most, so they aren't forced to drain their savings or sell assets to handle your final affairs.
This is where a guaranteed life insurance policy really shines. It delivers a specific, tax-free cash payout that your loved ones can use right away, taking the financial pressure off during an already stressful time. This is especially crucial for homeowners and renters here, who often face their own unique insurance headaches.
Many homeowners in high-risk zones, for instance, have to rely on the California FAIR Plan for fire insurance, which then must be paired with separate liability coverage. Similarly, securing comprehensive renters insurance can be complex.
A stand-alone guaranteed life insurance policy simplifies things beautifully. It keeps the money for your final expenses completely separate from any complex home insurance or property claims. It creates a clean, dedicated financial cushion, giving your family one less thing to worry about.
Ready to Find Your Policy? Here’s How We Can Help.
Knowing the ins and outs of guaranteed life insurance is a great first step. But the real goal is turning that knowledge into a safety net that protects your family. Now that you have a solid idea of how these policies work, the next move is finding the one that truly fits your life here in California.
That's where we come in. At Mai & Associates, our job is to make that happen. We know that life insurance is more than just a piece of paper—it’s the peace of mind that comes from knowing your loved ones will be okay financially. We’re here to make the whole process clear, simple, and effective.
Your Path to Coverage Made Easy
We’ve made our process as straightforward as the policies themselves. Forget spending hours digging through confusing insurance documents or bouncing between a dozen different websites. We’ll do all the legwork for you.
Our agents live and breathe the California insurance market. We understand the nuances of securing not just life insurance, but also affordable auto insurance and home insurance from Glendale to Escondido. By working with a broad network of top-rated carriers, we can quickly compare rates and policy details, laying out your best options without any sales pressure.
Taking the next step shouldn't feel overwhelming. With a little help, you can go from wondering to knowing your final wishes are covered, often in the same day.
We believe in giving you clear, honest information so you can choose with confidence. That’s why we offer same-day quotes, so you can see just how affordable this crucial protection really is.
Why Partner with a Local California Agency?
When you work with a local agency, you’re getting help from people who actually get it. We understand the financial realities of living in our state. We’re not just here to sell a policy; we’re here to build a relationship and help with all your insurance needs, whether it's for your home, car insurance, or renters insurance.
Here’s what you can expect from us:
- Expert Guidance: Our licensed agents will answer every question, helping you match a policy to your budget and your goals.
- Side-by-Side Comparisons: We do the shopping for you, bringing you competitive quotes from multiple trusted insurance companies.
- We Speak Your Language: We’re proud to serve our diverse communities with support in English, Spanish, Armenian, Russian, and Vietnamese.
- Right in Your Backyard: With offices in Glendale, Westlake Village, Escondido, and Costa Mesa, we’re a part of the neighborhoods we serve.
Choosing a guaranteed life insurance policy is a big decision, but it doesn't have to be a difficult one. Let us help you take this step with confidence.
When you're ready to explore your options, it's easy to request your personalized insurance quote and get started.
Frequently Asked Questions
It's only natural to have a few questions when you're looking at something as important as life insurance. Let's tackle some of the most common ones we hear about guaranteed life insurance here in California to clear things up.
Can I Still Be Denied Coverage?
It’s highly unlikely, but it can happen in a couple of very specific situations. Guaranteed issue policies live up to their name—no health questions, no medical exams. The biggest hurdle is age; you generally need to be between 50 and 85 years old to qualify.
The only other real reasons for denial would be clear signs of fraud on your application or if you live somewhere the insurance company doesn’t operate. But for almost everyone who fits the age bracket, getting approved is a sure thing.
What Happens If I Stop Paying My Premiums?
This is a critical point. If you stop making payments, your policy will eventually lapse. Once it lapses, the coverage ends, and your beneficiaries won't receive the death benefit you planned for them.
Since these are whole life policies, they do build up a small amount of cash value. If you've been paying for a while, you might be able to get that cash value back, but it will be a fraction of the death benefit. The key is to keep up with payments to ensure your loved ones are protected.
Can I Access the Cash Value of My Policy?
You can. One of the built-in features of guaranteed whole life insurance is that it slowly accumulates cash value. You can usually take out a loan against this value if you need to.
Just remember, any loan you take out—plus the interest it accrues—will be subtracted from the final death benefit if you don't pay it back.
Think of the cash value as a small, accessible savings component built into your policy. It's there for emergencies, but its main purpose is to support the long-term structure of the policy itself.
How Much Does Guaranteed Life Insurance Cost?
The price tag really depends on your age, gender, and how much coverage you want. Because the insurance company is taking a big risk by not asking about your health, the premiums are higher than for medically underwritten plans.
As a ballpark figure, a $10,000 policy for a 65-year-old could run anywhere from $50 to $100 a month. The good news is that the younger you are when you lock in your policy, the lower your rate will be for life.
Want to dig deeper? We've answered even more questions on our full FAQ page.
Getting the right California insurance isn't just a transaction; it's a vital step in protecting your family's future. The team here at Mai & Associates is committed to helping our fellow Californians find affordable, solid policies for all their auto insurance, home insurance, renters insurance, and life insurance needs.
Let us make it easy for you. Visit us at https://cahomeauto.com to compare rates and get a no-obligation quote today.