Free Look Period: A California Insurance Guide
You bought a policy, the email arrived, and then the second-guessing started.
Maybe it’s a California life insurance policy you signed after a long workday. Maybe it’s a new homeowners policy because your old carrier changed terms. Maybe you finally found car insurance or renters insurance that fit your budget, but once the policy documents showed up, the details felt different than what you expected.
That’s where the free look period matters. It gives you time to slow down, read the policy, and decide whether you want to keep it. For California residents, that can be especially important when you’re comparing life insurance, reviewing home insurance in a wildfire-prone area, or trying to avoid a coverage gap while moving in or out of a FAIR Plan setup.
What Is An Insurance Free Look Period
An insurance free look period is a short review window after you receive your policy documents. It functions as a legal return window for an insurance contract.
If you read the policy and decide it isn’t right for you, the free look period gives you a way to cancel. This isn’t a courtesy from an insurance company. It’s a consumer protection built into insurance rules for many policies.
A lot of people get tripped up by the name. “Free look” sounds informal, almost like marketing language. It’s really about your right to review the contract after delivery, when you can finally see the full wording, exclusions, riders, and cancellation terms in black and white.
Why this right matters
Insurance can feel simple when you’re getting a quote and much more technical once the policy arrives.
That’s true with:
- Life insurance, where beneficiaries, riders, and premium structure matter
- Home insurance, where exclusions and endorsements can change what’s covered
- Renters insurance, where personal property and liability limits may not match your needs
- Auto insurance or car insurance, where deductible choices and optional coverages deserve a second look
For California residents, this review step matters even more when you’re dealing with wildfire exposure, earthquake questions, lender requirements, or a tight budget.
Free look means you don't have to rely only on the sales conversation. You get time to inspect the actual policy.
If you want to get familiar with common insurance terms before reviewing your documents, a plain-English insurance glossary can help.
Understanding Your Right to a Full Refund
A California homeowner in a wildfire-prone area might apply for life insurance on Monday, feel relieved on Tuesday, and then spot a problem on Friday after the policy arrives. Maybe the premium is higher than expected. Maybe a rider is missing. Maybe the coverage no longer fits because the mortgage, the California FAIR Plan, and other household costs already stretch the budget. The free look period is the consumer protection that gives you room to slow down and correct that decision without losing your premium.
This right protects your money if you cancel on time.
State rules vary, but California gives life insurance buyers a stronger review window than many states do. As noted earlier, California’s life insurance free look period is longer than the basic period many consumers see elsewhere, which gives you more time to read the contract carefully instead of rushing through it.
The date that matters most
The deadline usually starts when the policy is delivered to you, not when you applied or paid.
That distinction causes confusion all the time. People often focus on the application date because that is when the process felt “official.” But the review period is tied to delivery because that is when you can finally inspect the actual contract, page by page, including riders, exclusions, and cancellation language.
A useful comparison is understanding a company's refund policy. Timing matters, proof matters, and the written terms control the outcome. Insurance adds another layer because the contract is regulated and the amount of money at stake can be much larger.
Why the refund right matters in real life
A full refund is more than a nice perk. It gives you a short window to catch mismatches before they become expensive mistakes.
That matters for Californians who are already juggling risk decisions at home. If you live in an area with wildfire concerns, earthquake questions, or FAIR Plan limitations, your insurance choices often affect each other. A life policy that looked affordable during the quote stage may feel different once you review the final paperwork alongside home, auto, or even California renters insurance options for family members in the same household.
Here is the practical point. During the free look period, you are still in the inspection phase. Once that window closes, canceling can have very different financial results depending on the policy terms.
What you should keep
Save anything that proves delivery.
That can include the envelope, a delivery email, a portal notification, or a timestamp showing when the insurer made the policy available. If there is ever a dispute about whether you canceled in time, that record helps establish your deadline.
If you are unsure whether your clock started on the delivery date, issue date, or effective date, ask the insurer to confirm the cancellation deadline in writing before you act.
California Free Look Periods for Your Insurance Policy
California gives consumers stronger protection than many people realize, especially for life insurance and annuities.
Under Cal. Ins. Code § 10127.10, California requires a 30-day free look period for life insurance and annuities, starting from policy receipt, as described in this California-specific discussion of the statute.
That longer window is useful because life insurance contracts can be dense. Riders, exclusions, premium schedules, and conversion features often make more sense when you read them slowly, not during a quick application call.
What California residents should know
If you live in California, don’t assume every policy type works exactly the same way.
For life insurance and annuities, the state’s rule is clear. You have a legally recognized review window from policy receipt.
For auto insurance, home insurance, and renters insurance, the situation is more policy-specific. These products may have cancellation options and refund terms, but they aren't always structured under the same free look framework as life insurance. In practice, you need to read the cancellation section of the contract and confirm the insurer’s process.
That’s why someone shopping for California car insurance or homeowners insurance should never assume a “30-day free look” applies just because they heard the phrase used broadly online.
Typical Free Look Periods in California by Policy Type
| Insurance Type | Typical Free Look Period in California | Governed By |
|---|---|---|
| Life insurance | 30 days from policy receipt | California law under Cal. Ins. Code § 10127.10 |
| Annuities | 30 days from policy receipt | California law under Cal. Ins. Code § 10127.10 |
| Auto insurance | Policy-specific cancellation terms vary | Insurer contract language and policy cancellation provisions |
| Home insurance | Policy-specific cancellation terms vary | Insurer contract language and policy cancellation provisions |
| Renters insurance | Policy-specific cancellation terms vary | Insurer contract language and policy cancellation provisions |
Where people get confused
The confusion usually comes from mixing up two different ideas:
- A legally mandated free look period
- A cancellation option offered under the policy
Those aren't always the same thing.
A California life insurance buyer can usually point to a defined legal window. A California auto insurance or renters insurance customer may instead need to review the policy’s cancellation wording and ask how refund handling works if they cancel shortly after purchase.
If you're comparing personal property coverage, liability limits, and landlord requirements, this guide to renters insurance in California can help you spot issues before they become an expensive surprise.
If you’re buying any policy in a hurry, treat the first review as incomplete. The real review starts when the full contract arrives.
Using Your Free Look Period Strategically in California
The free look period is widely considered an exit hatch. In California, it can also be a decision-making tool.
That matters most for homeowners in higher-risk areas. If your property faces wildfire concerns, earthquake questions, or FAIR Plan complexity, the free look period gives you a short but valuable chance to verify that your coverage matches your risk.
For Californians in high-risk areas, the free look period can be critical for reviewing coverage gaps. Over 4.5 million structures in the state are threatened by wildfires, and using this review window to compare a new policy against California FAIR Plan options can help prevent underinsurance, according to this free look period discussion focused on high-risk property review.
How to use the review window well
Don’t spend the period asking only, “Should I cancel?”
Ask better questions:
- Does the dwelling coverage make sense: For home insurance, compare the declarations page against what you believe it would take to rebuild.
- Are the endorsements attached: If you expected specific protections or optional features, confirm they appear in the policy, not just in an email summary.
- Is there a mismatch with lender or landlord requirements: This is common with homeowners and renters insurance.
- Does the policy fit your current transition: If you’re replacing a prior policy, make sure cancellation timing doesn’t leave you exposed.
A California-specific warning
The phrase “risk-free” can be misleading if you’re changing property coverage.
If you cancel a new policy during the review period without confirming what happens to the old one, you could create a coverage gap. That’s especially dangerous for homeowners in wildfire-prone areas or for people coordinating private insurance with the FAIR Plan.
A simple example helps. A homeowner receives a new policy, reviews it, and decides the terms don’t work. If they cancel it but assume prior coverage automatically snaps back into place, they may be wrong. Insurance coverage doesn't work like pausing a streaming subscription.
Check continuity before you cancel. Refund rights are helpful, but they don't protect you from an uninsured loss.
Best use of the free look period
For California homeowners, the smartest use of the free look period is often side-by-side verification:
- Compare the declarations page
- Compare exclusions
- Compare deductible structure
- Check any wildfire or earthquake-related concerns
- Confirm whether your policy combination leaves a gap
For life insurance, use the period differently. Review beneficiaries, rider language, premium commitment, and whether the policy still fits your family’s budget if nothing changes over time.
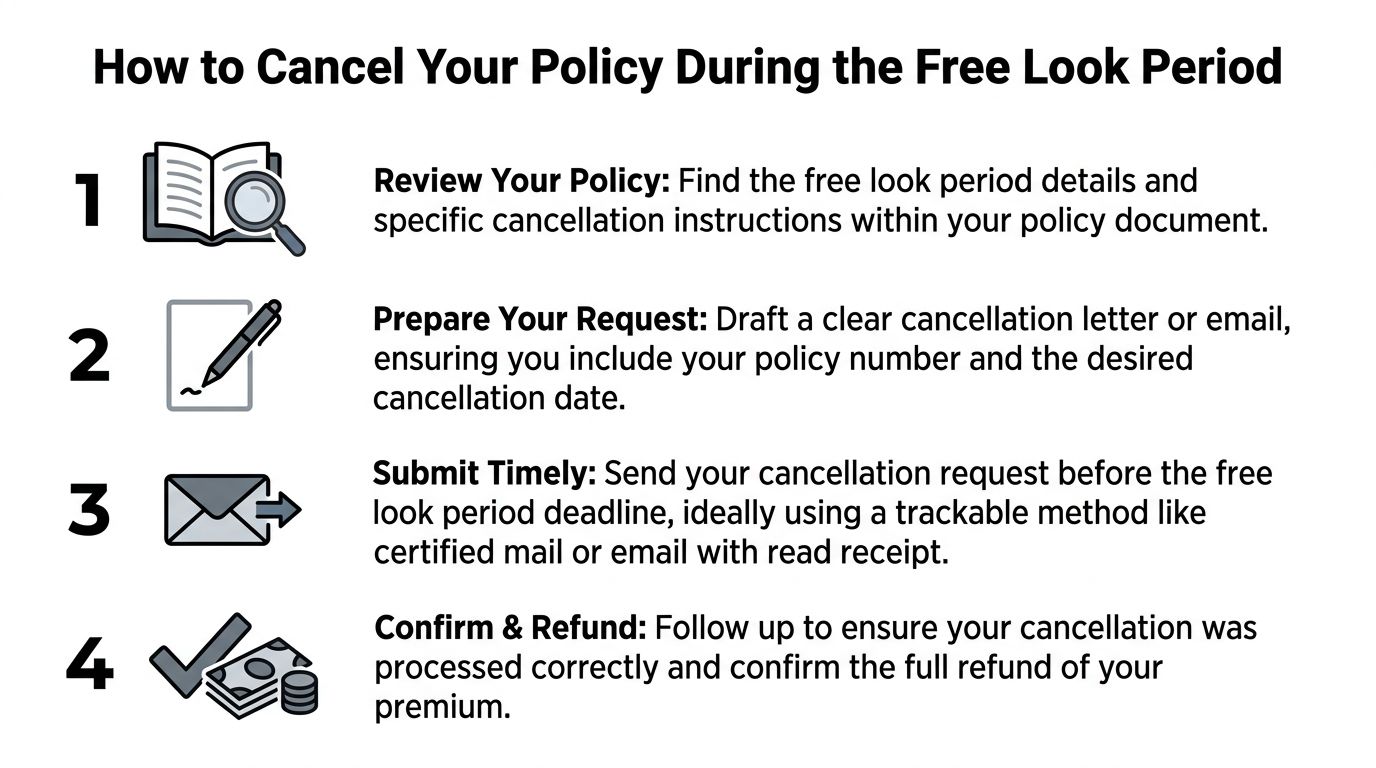
How to Cancel Your Policy During the Free Look Period
A California homeowner in a wildfire area buys a new life insurance policy while also trying to sort out home coverage, FAIR Plan questions, and rising premiums. The policy arrives, and after reading the details, they realize the coverage is not what they expected. The free look period is the exit door, but only if they use it correctly and on time.
If you decide to cancel, treat it like returning an expensive appliance. Keep the receipt, follow the store's instructions, and get written proof the return was accepted. Insurance works the same way. A clear paper trail matters.
For life insurance, the free look period is usually your cleanest chance to cancel and ask for your premium back. After that window closes, the process can change a lot, so timing matters.
Step 1
Find the insurer's cancellation instructions right away.
Check your policy packet, welcome email, or online account for terms like:
- Cancellation
- Free look
- Right to examine
- Notice of cancellation
- How to terminate coverage
If the wording feels vague, ask the company to send the instructions by email. A phone call helps. Written instructions help more.
Step 2
Write a short cancellation request with the facts the insurer needs.
Keep it simple. Include:
- Your full name
- Policy number
- Date you received the policy
- A statement that you are cancelling within the free look period
- The date you want cancellation to take effect
- Your contact information
For California residents comparing life insurance while also juggling property issues, this step keeps small mistakes from turning into bigger ones. If you are in a high-risk area and making several insurance decisions at once, organization matters more than speed alone.
Send the request in a way you can prove later. Certified mail, secure portal message, or email with a saved copy all work well.
Step 3
Submit the request before the deadline. Earlier is better.
Waiting until the last day creates avoidable problems. Email can get missed. Portals can time out. Mail can be delayed. If the company accepts digital delivery, send it early and keep screenshots showing the date and time.
If you still need help comparing options before you cancel, use this California insurance quote page for side by side review.
Step 4
Stay with it until you receive written confirmation.
You want two pieces of proof:
- Confirmation that the policy was cancelled
- Confirmation that the refund is being processed
If the insurer asks for another form, a signature, or the original policy document, respond quickly and keep copies of everything you send.
Sample cancellation letter
[Your Full Name]
[Your Address]
[City, State, ZIP]
[Email Address]
[Phone Number]
[Date]Insurance Company Name
Attn: Policy Cancellation Department
[Company Address]Re: Cancellation During Free Look Period
Policy Number: [Your Policy Number]I am requesting cancellation of the above policy during the applicable free look period. I received the policy on [date received]. Please cancel the policy and confirm that a full refund of premiums paid will be issued.
Please send written confirmation of cancellation and refund processing to me at the contact information above.
Sincerely, [Your Name]
A California caution
If you are cancelling auto, home, or renters coverage, confirm replacement coverage first.
That point is especially important for people in wildfire zones, homeowners piecing together private coverage with the FAIR Plan, and drivers who cannot afford even a short lapse. Canceling one policy does not automatically restore an older one. Insurance does not snap back into place like reopening a paused app.
Keep the refund in one hand and continuous coverage in the other. That is the safest way to use the free look period.
Let Mai & Associates Help You Compare with Confidence
The best free look strategy is getting the policy right before the pressure sets in.
That means comparing options carefully, reviewing the declarations page, asking direct questions, and checking how a policy handles California-specific risks. Shoppers who want auto insurance, home insurance, renters insurance, car insurance, or life insurance usually make better decisions when they can compare more than one carrier at the same time.
That’s where working with a California agency can help. Mai & Associates gives residents a straightforward way to review options, ask coverage questions, and request a no-pressure quote through this insurance quote page.
Why comparison matters in California
A lower premium doesn’t always mean better value.
For example, one home policy may look affordable until you review exclusions. One car insurance option may fit your budget but leave you uncomfortable with the deductible. One life insurance policy may sound fine in summary form but feel very different once you read the contract.
Where guidance helps most
A California resident often needs more than a quick price check.
That’s especially true when you’re dealing with:
- Wildfire risk and FAIR Plan questions
- Earthquake concerns
- Renters insurance requirements from a landlord
- Life insurance choices that affect long-term family planning
- Auto insurance decisions for a new driver or changed commute
A good advisor helps you understand the policy before you ever need to think about cancelling it. If you do need to use the free look period, clear guidance and fast action make the process smoother.
Frequently Asked Questions About The Free Look Period
A few questions come up again and again, especially from California policyholders trying to avoid mistakes.
What if I have a claim during the free look period and then want to cancel
That can get complicated fast.
If a loss happens, you should report it according to the policy terms. After that, ask the insurer how a cancellation request affects the policy and claim handling. Don’t assume the free look period works like a no-strings-attached trial once coverage has already been used.
Does the free look period apply to renewals
Usually, people should assume the free look period is tied to a new policy, not an automatic renewal, unless the contract or insurer says otherwise.
If you renewed a policy and want out, check the renewal documents and cancellation section right away. The answer often depends on the product and the insurer’s wording.
Is free look period the same as a cooling-off period
In everyday conversation, yes, people often use those terms the same way.
They both describe a short review window after purchase or delivery when the buyer can reconsider. Insurance documents may prefer one term over the other, so always read the policy language itself.
Can an insurance company refuse to cancel if I’m within the free look period
If you are within the applicable free look window and you follow the required cancellation process, the insurer generally shouldn’t treat that request like an optional favor.
The practical issue is usually not refusal. It’s proof. If there’s a dispute, your records matter. Keep copies of emails, portal messages, mailing receipts, and confirmation notices.
What’s the safest way to protect myself during the free look period
Use a simple checklist:
- Save the delivery record
- Read the declarations page first
- Check exclusions and endorsements
- Ask questions in writing
- Do not cancel old coverage until replacement coverage is confirmed
If you want answers to other common coverage questions, this California insurance FAQ page is a useful next stop.
If you're comparing California auto insurance, home insurance, renters insurance, car insurance, or life insurance and want help reviewing your options before you commit, Mai & Associates can help you compare coverage clearly and confidently. Their team works with California residents who need practical guidance, especially when policies involve wildfire risk, FAIR Plan questions, or side-by-side quote review.