Final expense life insurance: A key part of your California insurance plan
When people talk about final expense life insurance, they're really talking about a specific kind of whole life insurance policy built to handle end-of-life costs. Think of it as a dedicated financial safety net, designed to cover things like funeral services, lingering medical bills, or credit card balances, and an essential component of a complete California insurance portfolio.
The whole point is to make sure your loved ones aren't stuck with a sudden financial burden during an already stressful time. Its biggest draw is how easy it is to get—most policies don't even require a medical exam to get approved. It complements other essential coverages like auto insurance and home insurance by protecting your family's savings from being drained by final costs.
What is Final Expense Life Insurance, Really?
Let’s cut through the insurance-speak. Final expense life insurance isn't some complex financial instrument. It's a straightforward plan with one very clear job, working alongside your broader life insurance strategy in California.
Imagine you know a big, inevitable expense is coming down the road—like replacing the roof on your house. Instead of leaving your family to scramble for the cash when the time comes, you set aside a specific fund just for that purpose. That’s exactly what this insurance does for your final expenses.
This approach is especially practical for seniors here in California. When you pass away, the policy pays out a lump sum of tax-free cash directly to the person you name as your beneficiary. They can then use that money immediately to handle whatever needs to be paid, without red tape or delays.
To give you a quick overview, here are the core features:
Final Expense Insurance At a Glance
| Feature | Description |
|---|---|
| Policy Type | A form of permanent whole life insurance. |
| Primary Goal | Covers end-of-life costs like funerals and medical bills. |
| Coverage Amounts | Typically smaller, from $2,000 to $50,000. |
| Premiums | Fixed for life; they will never increase. |
| Medical Exam | Usually not required; approval is based on a health questionnaire. |
| Payout | A tax-free, lump-sum cash benefit paid to your beneficiary. |
Ultimately, this policy acts as a shield, protecting your family’s finances when they need it most.
The Purpose Behind the Policy
The main goal here is to prevent your family from feeling financial pressure during a difficult time. Rather than draining their savings—or worse, going into debt to pay for final bills—they have a dedicated resource ready to go. This ensures that assets protected by home insurance or funds earmarked for car insurance deductibles remain untouched.
This money is most often used for:
- Funeral and Burial Costs: In California, these expenses can easily run from $7,000 to over $12,000.
- Unpaid Medical Bills: Covering co-pays, deductibles, and other healthcare costs left behind.
- Credit Card Debt: Clearing any outstanding balances on personal credit cards.
- Legal Fees: Handling the costs associated with settling an estate.
This targeted design makes it a smart addition to any financial plan, particularly for those who might not have other kinds of life insurance. If you're curious about the broader landscape, our guide on life insurance in California breaks down all the options.
A Growing Need for Simple Solutions
More and more people are looking for simple, no-fuss ways to plan for the inevitable. This is driven by an aging population and the steadily rising cost of funerals. The global market for this type of insurance was valued at USD 17.46 billion in 2026, which shows just how many people are seeking out these plans.
A huge part of the appeal comes down to accessibility. Research shows that 48% to 86% of Americans aged 55-64 have pre-existing conditions, which can make getting traditional insurance a real challenge. Final expense policies, which often skip the medical exam, provide a perfect solution. For California families, this means peace of mind is within reach. You can learn more about these market trends from this in-depth final expense insurance growth report.
In essence, a final expense policy is about proactive planning. It's a final gift of thoughtfulness, ensuring your legacy is one of peace of mind, not financial stress.
How a Policy Protects Your Family From Start to Finish
Think of a final expense policy not just as an insurance document, but as a promise you make to your family. Seeing how it works from the day you sign up to the day it pays out really shows how much security it can provide when they need it most. The whole process is designed to be simple, cutting through the usual red tape of traditional insurance.
This diagram breaks down the straightforward, three-step journey of a final expense policy.
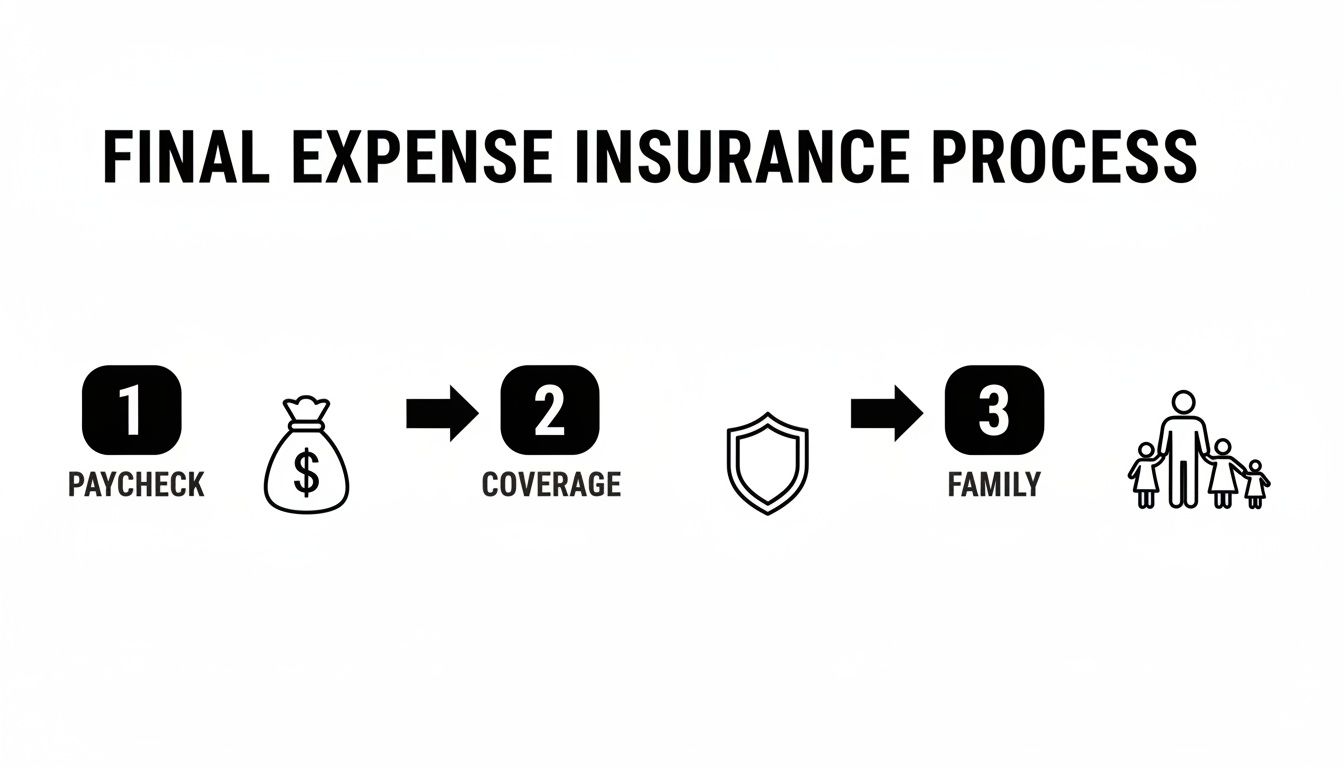
It’s a clear visual of how your steady premium payments build a reliable financial safety net for the people you care about.
The Simple Application Process
One of the best things about final expense life insurance is how refreshingly easy it is to get approved. Forget the invasive medical exams, blood tests, and long waits that come with other types of life insurance. These policies were built to be accessible.
For California residents, most plans fit into one of two buckets:
- Simplified Issue: You’ll answer a handful of health questions on the application, but that’s it—no doctor’s visit needed. Approvals often come back in just a few days.
- Guaranteed Issue: If you have more serious health issues, these policies are a fantastic option. They ask no health questions at all. As long as you fall within the eligible age range (usually 50-85), your approval is practically guaranteed.
This streamlined approach means that many seniors who thought they were uninsurable can finally get the meaningful coverage they deserve.
During the Life of the Policy
Once your policy is in force, it’s all about consistency and predictability. You just make your regular premium payments to keep the coverage active.
The best part? Your premiums are fixed. The rate you lock in on day one is the same rate you'll pay for the rest of your life. It will never go up, no matter how old you get or if your health changes.
Because this is a type of whole life insurance, the policy also slowly builds cash value over the years. This is a living benefit you can tap into, like a small loan, if an emergency pops up. Just remember that borrowing from it will reduce the final payout if the loan isn't repaid.
This structure gives you incredible stability. You know exactly what you'll pay, and you know the coverage will be there for your entire life as long as premiums are paid. It adds a powerful element of certainty to your financial plan.
The Final Step: The Payout
This is where the policy truly delivers on its promise. When the insured person passes away, the beneficiary—the person you’ve chosen to receive the money—simply files a claim with the insurance company.
Insurance carriers know how time-sensitive this is. They work to process these claims very quickly, often within a few days of receiving the necessary paperwork, like the death certificate.
The beneficiary receives the death benefit as a tax-free, lump-sum payment. They get the full policy amount, and not a penny of it is lost to taxes. They have complete freedom to use this money for whatever is most pressing, such as:
- Paying for the funeral and burial right away.
- Clearing out any final medical bills or credit card balances.
- Taking care of legal fees to settle the estate.
- Covering daily living expenses while they grieve.
Getting these funds quickly can lift a massive weight off their shoulders, especially since it avoids the delays of waiting for Life Insurance Proceeds and Probate. This immediate financial relief lets your family focus on supporting each other, not on scrambling to find money for final expenses. From beginning to end, the policy is there to act as a reliable safeguard for your loved ones.
Decoding Coverage Amounts and Costs in California
Let's get down to the brass tacks: how much final expense insurance do you actually need, and what’s it going to cost here in California? This is often where people feel a bit overwhelmed, but it’s simpler than you might think. The whole point is to find that sweet spot—a policy that gives your family real protection without making a dent in your own budget.
Unlike a massive term life policy designed to replace a lifetime of income, final expense life insurance is focused and specific. It’s built to deliver a manageable lump sum of cash right when your loved ones need it the most, no strings attached. It is a critical piece of the California insurance puzzle, alongside policies like home insurance and renters insurance.
How Much Coverage Is Enough?
Most final expense policies offer a death benefit somewhere between $5,000 and $25,000. You might find some that go as high as $50,000, but the core idea is to match the coverage to the actual bills your family will face. This isn't about guesswork; it's about practical planning.
So, how do you land on the right number? Start by adding up these common end-of-life costs:
- Funeral and Burial Expenses: The average funeral in California can easily run over $9,000. Depending on the specifics—casket, service, burial plot—that number can climb even higher.
- Medical Bills: Even with great health insurance, there are often leftover co-pays, deductibles, and other medical debts from final care.
- Outstanding Personal Debts: Think about any lingering credit card balances or small personal loans. A final expense policy can prevent these from becoming a burden on your family.
- A Small Financial Cushion: It’s smart to add a little extra to the total. This gives your loved ones some breathing room for unexpected costs or even serves as a small, heartfelt inheritance.
Tallying these up gives you a realistic target for your coverage amount, ensuring you’re getting exactly what’s needed.
A common mistake is to either under-insure, leaving a financial gap, or over-insure, paying for more coverage than is necessary. A well-chosen policy covers expected costs plus a small buffer, providing an efficient and affordable safety net.
Factors That Influence Your Monthly Premium
Once you have a coverage amount in mind, the next logical question is: what will it cost me each month? Insurance companies look at a few key factors to determine your premium. It's all about assessing risk.
Here’s what they’ll consider:
- Your Age: This is the big one. The younger you are when you lock in your policy, the lower your rate will be for life.
- Your Gender: On average, women live longer than men. Because of this, females usually pay slightly less for the same amount of coverage.
- Your Health: While there’s no medical exam required, you will answer a few health questions. Being in better health generally translates to a lower premium.
- The Coverage Amount: This one’s straightforward—a $20,000 policy will cost more per month than a $10,000 policy.
Sample Monthly Premiums for Californians
To give you a real-world idea of costs, we’ve put together a table showing some estimated monthly premiums for a typical $15,000 final expense policy in California.
Keep in mind these are sample rates for non-smokers. Your actual premium will depend on your specific health profile and the insurance carrier you choose.
Sample Monthly Premiums for Final Expense Insurance in California
| Age Group | Average Monthly Premium for Male | Average Monthly Premium for Female |
|---|---|---|
| 60-65 | $65 - $85 | $50 - $70 |
| 66-70 | $85 - $110 | $70 - $90 |
| 71-75 | $110 - $145 | $90 - $120 |
| 76-80 | $145 - $200 | $120 - $160 |
These policies fill a critical gap, especially since only about half of Americans have any life insurance. With the average funeral bill in California exceeding $9,000, a final expense plan empowers families to prepare. It's no surprise that coverage tiers below $10,000 are popular for those on a tight budget, making it easy for seniors to get protected without a medical exam. You can explore more of these insightful final expense insurance market trends to see how they’re shaping financial planning.
Choosing the Right Tool for the Job
Not all life insurance policies are built the same. Picking the right one is a lot like choosing the right tool for a specific task—you wouldn't use a sledgehammer to hang a picture frame. In the same way, using a massive term life policy when all you need is coverage for final expenses can be a costly mistake.
For Californians trying to get their affairs in order, understanding these distinctions is the first step toward making a confident choice for your family's future. Let's break down the key differences.
Final Expense vs. Term Life Insurance
Think of term life insurance like renting an apartment. You get a huge amount of protection for a set period—usually 10, 20, or 30 years—for a very low price. It’s fantastic for covering big, temporary responsibilities like a mortgage or your kids' college tuition if you were to pass away during your peak earning years.
But here’s the catch: once the term is up, the coverage is gone. If you outlive the policy, there's no payout. This makes it a poor fit for covering funeral costs, which are a certainty, not a "what if."
Final expense insurance, however, is like owning your home. As long as you keep up with the premiums, the policy is yours for life. The death benefit is smaller, but it’s specifically designed to handle those final bills. For many California seniors, its permanent nature and laser focus make it a much more practical solution.
Final Expense vs. Traditional Whole Life Insurance
This is where people sometimes get tripped up, because final expense insurance is technically a type of whole life insurance. The easiest way to think about it is that all squares are rectangles, but not all rectangles are squares. Final expense is the specialized "square," while traditional whole life is the broader "rectangle."
Traditional whole life is a heavy-duty financial tool. It’s usually sold for large-scale estate planning and wealth-building, with coverage amounts often starting at $100,000 and a significant cash value component meant to grow over decades. The premiums are, of course, much higher to support these features.
Final expense policies are a lean, simplified version. They strip away the complex investment angles to do one job perfectly: provide affordable, permanent coverage for final costs. The underwriting is simpler, and the smaller face amounts make it accessible for seniors who don't need or want a massive policy.
The key takeaway is purpose. Traditional whole life is for large-scale legacy planning, while final expense insurance is for precise, immediate, end-of-life financial relief.
Why Specialization Matters
The numbers don't lie—people are actively seeking out these specialized policies. The market for final expense plans recently saw a 10% jump in policies sold and a 16% rise in premiums, which points to some serious demand. Globally, permanent policies make up a staggering 71% of the life insurance market, showing a clear preference for lifelong coverage.
With funeral costs climbing by 5-7% every year, it’s easy to see why a focused policy has become so crucial for financial peace of mind. For a deeper dive, you can check out this global final expense insurance forecast.
As you explore your options, working with the right professionals can make all the difference. Some people find value in services from an Acceptance Agency Insurance and Notary to help sort through the details. This is about more than just buying a policy; it's about finding a partner to help you secure that peace of mind.
To learn more, check out our comprehensive guides on California insurance and get a clearer picture of your options.
Finding Your Policy with a California Expert
Knowing your options is one thing, but taking that next step is what really protects your family. The process of getting final expense life insurance shouldn't be confusing or intimidating. It should give you confidence. Working with a local California team like ours at Mai & Associates means you'll have a real person guiding you through your total California insurance needs.
Our whole approach is built on trust and clarity. We're committed to helping you find the right policy by comparing plans from several top-rated insurance companies. In many cases, we can get you same-day quotes, so you can move forward quickly and feel good about your choice.
A Personalized Approach for California Families
California is incredibly diverse, and your insurance advice should be too. To make sure every conversation is comfortable and clear, we offer support in English, Spanish, Armenian, Russian, and Vietnamese.
This personal touch goes a long way. We take the time to really listen and understand your specific budget, family dynamics, and what you’re trying to accomplish. The goal is simple: match you with a policy that just feels right, so you can have genuine peace of mind.
True financial security comes from having a plan that covers all your bases. It's not just about one policy, but about how all your protections work together to safeguard what matters most.
A Complete Review of Your Insurance Needs
Your financial safety net is made up of more than just a single policy. Because we're a full-service California insurance agency, we can look at the bigger picture for you. We often review a client's entire insurance portfolio to find gaps or even ways to save money.
We help Californians with all sorts of protection:
- Auto Insurance: Getting the right coverage for navigating California's busy roads.
- Home Insurance: Protecting your biggest asset, including specialized help for high-risk wildfire areas and the California Fair Plan.
- Renters Insurance: Making sure your personal property and liability are covered.
- Life Insurance: From final expense plans to larger policies, we make sure your coverage lines up with your family’s long-term needs.
This holistic review ensures your final expense plan fits perfectly within a solid financial strategy. By looking at everything from your car insurance to your home insurance, we help make sure your family is protected from every angle.
Ready to talk to a local expert you can trust? You can easily get a personalized insurance quote from Mai & Associates to start the conversation today. We keep the process simple, respectful, and focused on what's best for you.
Your Top Questions About Final Expense Insurance, Answered
It's completely normal to have a few questions lingering, even after you've got the basics down. Let's dig into some of the most common things people ask about final expense life insurance in California. My goal here is to clear up any confusion so you can move forward with total confidence.
Do I Have to Wait for My Coverage to Kick In?
That really boils down to the specific policy you get approved for. This is a common point of confusion, but it’s a critical detail for the people you leave behind.
- Simplified Issue Plans: These are the most common. You'll answer a few basic health questions, but there's no medical exam. If you qualify, your full death benefit is active from day one. No waiting period.
- Guaranteed Issue Plans: If you have more serious health concerns, this might be the right fit. There are zero health questions asked. The trade-off is a two to three-year waiting period, often called a "graded death benefit."
So, what does "graded" mean? If death from natural causes happens during that initial two-to-three-year window, your beneficiary gets back all the premiums you paid, usually plus a little extra, like 10% interest. However, if the death is from an accident, the full policy amount is paid out, even on day one.
Can My Family Use the Money for Anything?
Yes, and this is a huge benefit. While the policy is designed to handle things like funeral bills and final medical expenses, the payout is simply a tax-free cash payment.
Your beneficiary gets a lump sum with no strings attached. They can use it to pay for a funeral, settle credit card debt, pay off a car insurance loan, or cover their own mortgage payment for a few months. It's their decision. This puts it worlds apart from pre-need funeral plans, which tie your money to one specific funeral home for a pre-selected package of services.
What Happens if I Can’t Afford the Premiums Anymore?
Life happens, and your financial situation can change. Because final expense is a type of whole life insurance, it builds cash value over the years, which gives you a safety net.
If you hit a point where the premiums are no longer affordable, you don't automatically lose everything you've paid in. You generally have a few solid options:
- Cash Out the Policy: You can choose to surrender the policy and walk away with its accumulated cash value.
- Let the Policy Pay for Itself: You might be able to use the cash value you've already built up to cover the premium payments for a while.
- Take a "Paid-Up" Policy: This is a great feature. You can stop paying premiums altogether and keep a smaller, but fully paid-for, death benefit for the rest of your life.
The best move depends on your unique situation, so it's always smart to talk it through with your agent.
Am I Too Old or Sick to Get a Policy in California?
Almost certainly not. These policies were created specifically for seniors, typically people between 50 and 85. Even with common age-related health issues like diabetes, high blood pressure, COPD, or a history of heart problems, many Californians easily qualify for a simplified issue plan with immediate, day-one coverage.
For those with more complex or recent health challenges, a guaranteed issue policy is almost always an option. They accept everyone within the eligible age range, no matter their medical history. At Mai & Associates, our job is to check with all our carriers to find the best policy for your exact health profile. We firmly believe everyone deserves a way to find peace of mind.
For even more answers, we've put together a comprehensive list on our California insurance FAQ section.
Ready to see what your options look like? The team at Mai & Associates is here to give you straightforward, no-pressure help. We'll help you compare quotes from California's most trusted insurance carriers so you can protect what matters most. Visit us at https://cahomeauto.com to get your free, same-day quote.