Cheapest Car Insurance California: Save on Your Policy
Let's be honest, finding cheap car insurance in California can feel like a hunt for a mythical creature. You hear about these great low rates, but getting one for yourself seems impossible. The truth is, while companies like Wawanesa, GEICO, and Mercury often pop up as affordable options, the actual cheapest provider for you is entirely personal.
Getting the best deal on your California insurance isn't about finding a single "magic" company. It's about understanding what goes into your premium and then shopping smart for your auto, home, and renters insurance needs.
Your Guide to Affordable California Car Insurance
Figuring out car insurance costs in California can be a real headache. That final price you see on a quote isn't arbitrary; it’s a highly personalized number crunched from dozens of details about you, your car, and where you live. Think of it like a financial fingerprint—no two are exactly alike.
So, what's the secret to cracking the code? It's surprisingly simple: compare quotes from multiple carriers. This is the single most effective thing you can do for any type of California insurance, from auto to home. The insurer that gives your friend in San Francisco a fantastic deal might be one of the most expensive for you down in Orange County. You have to see the whole field to find the right fit.
Average Monthly Rates from Top Affordable California Insurers
To give you a starting point, here’s a look at what you might expect to pay with some of California's most budget-friendly insurers. Remember, these are just averages for a standard driver profile—your own rates will almost certainly be different.
| Insurance Provider | Average Full Coverage (Monthly) | Average Minimum Coverage (Monthly) |
|---|---|---|
| Wawanesa | $128 | $45 |
| GEICO | $142 | $48 |
| Progressive | $155 | $55 |
| Mercury | $160 | $61 |
| Auto Club (AAA) | $171 | $65 |
These numbers are a great baseline, but they underscore why shopping around is so critical. A few minutes of comparison could easily save you hundreds of dollars a year.
Key Factors That Shape Your Insurance Rate
Insurers are in the business of predicting risk. They use a specific set of factors to figure out how likely you are to file a claim, and that prediction becomes your premium.
While we'll dive deeper into these later, here are the heavy hitters:
- Your Driving Record: Nothing speaks louder than a clean record. It's your golden ticket to the lowest rates.
- Your Location: Where you park your car at night matters. Premiums can swing wildly from one ZIP code to the next based on local stats for theft, accidents, and even weather.
- The Vehicle You Drive: A sensible sedan costs less to insure than a high-performance sports car or a luxury SUV. The car's age, safety ratings, and typical repair costs all play a big role.
- Your Coverage Choices: This one's on you. Opting for basic state-minimum liability will always be cheaper than a comprehensive full coverage policy with low deductibles.
Unlocking Potential Savings
Beyond those main factors, discounts are where you can really start chipping away at your premium. Most people qualify for at least one or two but often don't know to ask.
Combining your auto insurance with a home insurance or renters insurance policy is almost always a guaranteed money-saver. Other common discounts include those for being a good student, maintaining a clean driving record for several years, or even taking a defensive driving course.
The real power comes not just from knowing who might be cheap, but understanding why your rate is what it is. Once you grasp that, you can find a California insurance provider that rewards your specific profile with genuine, long-term savings.
Understanding Your California Insurance Rate
Have you ever wondered what actually goes into the car insurance quote you receive? It's not just a random number. Think of your premium as a personalized "risk score" that insurance companies calculate specifically for you. Finding the cheapest car insurance in California isn't about getting lucky; it's about understanding how carriers build this score so you can take smart steps to improve it.
This score isn't some big secret, either. It’s based on a clear set of factors that predict how likely you are to file a claim. Once you start to break down this puzzle, you gain the power to influence your rate and find some serious savings on your California insurance policies.
The whole game really comes down to three main pillars: understanding what affects your rate, actively looking for discounts, and comparing quotes from different companies.
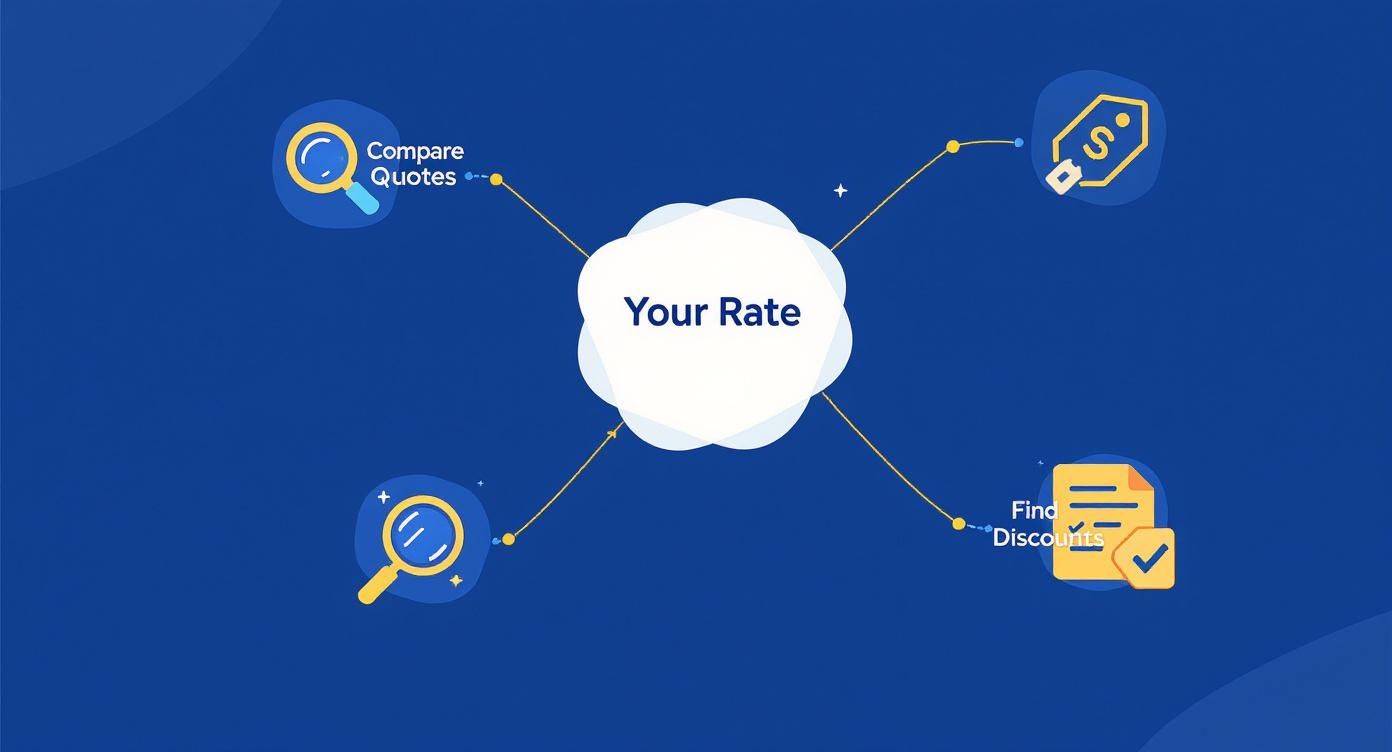
As you can see, your final rate is a direct result of these interconnected strategies. The more you engage with them, the more control you have over what you pay.
Your Driving Record and History
Of all the pieces in the puzzle, your driving record is the biggest one. Insurers see a clean record—no accidents, tickets, or DUIs—as the single best sign of a low-risk driver. Just one at-fault accident or speeding ticket can hike up your premium for three to five years.
On the flip side, a history of safe driving is your best negotiating tool. Most companies offer a major "Good Driver" discount, which is often one of the most effective ways to slash your car insurance bill. It's their way of rewarding you for being a responsible driver on California's hectic roads.
Where You Live and Park Your Car
It might sound strange, but your ZIP code has a huge impact on your insurance costs. Insurers are constantly analyzing local data, looking at things like vehicle theft rates, vandalism, and how often accidents happen in your specific neighborhood. This principle applies to home insurance as well, where local factors heavily influence your premium.
For example, a driver living in a dense urban center like Los Angeles will almost always pay more than someone in a quieter town like Bakersfield. Why? Because the statistical risk of something happening to their car is simply higher. This factor isn't about you—it's about the environment where your car spends its time.
The average cost of car insurance in California varies significantly by location and coverage. Full coverage averages $3,022 per year ($252 monthly), while minimum coverage is about $1,275 annually ($106 monthly). These figures show the real-world premium differences, with Los Angeles drivers paying an average of $3,066 annually, far more than the $1,820 average in San Diego. You can discover more insights about California insurance costs from Experian’s analysis.
The Vehicle You Choose to Drive
The car you get behind the wheel of directly affects your premium. Insurers look at a few key details about the vehicle itself:
- Cost to Repair: A luxury SUV or a car packed with specialized tech is going to be more expensive to fix after a fender bender. That means higher insurance costs.
- Safety Ratings: Cars that earn top safety ratings and have features like automatic emergency braking often qualify for discounts. They're just less likely to be in a serious crash.
- Theft Rates: Some models are just more popular with car thieves. If your car is a common target, you can expect your comprehensive coverage to cost a bit more.
- Engine Power: A high-performance sports car screams "risk" to an insurer. The potential for high speeds translates directly into a more expensive policy.
How Much You Drive Annually
Another key metric is your annual mileage. It's simple math for an insurer: the more time you spend on the road, the higher your chances of getting into an accident.
If you have a short commute, work from home, or use public transit most days, you could be in line for a low-mileage discount. Insurers see drivers who log fewer than 7,500 or 10,000 miles a year as a much lower risk.
Your Coverage Choices and Deductibles
The type and amount of coverage you choose is the one factor you have complete control over. Going with state-minimum liability will always be your cheapest option, but be warned—it offers very little protection if something serious happens. A full coverage policy with collision and comprehensive gives you real peace of mind but costs more.
You can also fine-tune your premium by adjusting your deductible, which is the amount you agree to pay out-of-pocket on a claim before your insurance pays the rest.
- A higher deductible (like $1,000) means you take on more of the initial risk, which in turn lowers your monthly premium.
- A lower deductible (like $500) means the insurer is on the hook for more, which increases your premium.
It’s all about finding the right balance for your budget and risk tolerance. By really understanding these individual factors, you can make informed decisions that put you back in the driver's seat of your insurance costs. For a deeper look into policy options, check out our other California insurance guides.
Meeting California's Minimum Insurance Requirements
First things first: you can't legally drive in California without car insurance. It’s not a friendly suggestion from the DMV; it's the law, and it exists for a very practical reason. The state wants to make sure that if you cause an accident, there's a financial backstop to cover at least some of the damage you're responsible for.
This baseline coverage is called liability insurance. Think of it as a safety net, but one that’s designed to catch the people you might accidentally harm, not you or your car. This is a critical point to grasp when you're on the hunt for the cheapest car insurance in California, because the state-minimum policy is a very thin blanket of protection.
Decoding the 15/30/5 Liability Rule
You'll often hear California's minimum requirements referred to as "15/30/5." It sounds like code, but it's really just shorthand for the dollar limits your insurance company will pay out if you're at fault in an accident.
Let's unpack what those numbers actually mean for you:
- $15,000 for Bodily Injury Liability per person: This is the most your policy will pay for a single person's medical bills if you injure them.
- $30,000 for Bodily Injury Liability per accident: If you injure two or more people, this is the total pot of money your insurance will pay for all of their medical expenses combined.
- $5,000 for Property Damage Liability per accident: This is the maximum your policy will pay to fix the other person's car or any other property you damage.
And the keyword here is maximum. If the bills from an accident go over these limits, the rest comes directly out of your pocket.
A Real-World Fender Bender Example
Let's play this out. Imagine you're in traffic and accidentally rear-end a late-model SUV. It's not a high-speed crash, but the two people in the other car complain of neck pain and get checked out at a hospital. Their SUV has some serious bumper and tailgate damage.
Here’s how a 15/30/5 policy would handle the aftermath:
- The other driver's medical bills hit $18,000. Your policy pays its $15,000 limit, and you're now on the hook for the remaining $3,000.
- The passenger's medical care costs $10,000. Your policy covers this in full.
- The total medical bills are $28,000, which is just under your $30,000 per-accident cap. You got lucky there.
- But the repair shop quotes $8,500 to fix the SUV. Your policy only covers $5,000 for property damage. You have to pay the other $3,500.
When all is said and done, this seemingly minor accident leaves you with a personal bill of $6,500. In a state with some of the highest medical and auto repair costs in the country, just carrying the minimum is a huge financial gamble.
The California Low Cost Auto Insurance Program
The state understands that for some people, even a bare-bones policy is a real financial strain. To address this, California created a special program to help.
The California Low Cost Auto Insurance Program (CLCA) is designed to give income-eligible drivers a way to get legal and stay on the road without breaking the bank.
This state-sponsored program is a lifeline, offering a basic liability policy for far less than you’d find on the open market. It's a smart solution that helps drivers stay insured, which makes the roads safer for every single one of us.
To get into the program, you have to meet certain income requirements, own a car valued under a specific amount, and maintain a good driving record. It’s an essential service that closes the gap for folks who might otherwise risk driving uninsured.
Comparing California's Most Affordable Insurance Companies
When you start shopping for the cheapest car insurance in California, you'll probably see the same names pop up over and over. While there’s no single "cheapest" company for absolutely everyone, a few providers have definitely earned a reputation for offering consistently competitive rates across the state. Instead of just looking at generic lists, let's dig into the key players most likely to give you a great quote.
Knowing who these companies are and what they’re good at gives you a huge head start. Rather than throwing quotes out into the void, you can start with a smart, well-researched shortlist of providers known for value. It's a targeted approach that saves time and seriously boosts your chances of finding a policy that fits your budget without all the usual hassle.
Top Contenders for Affordable Rates
Even though dozens of companies write auto insurance policies in California, three of them consistently come out on top for pricing. If you're serious about finding the best deal, these are the companies to check first.
- GEICO: Known for its easy-to-use website and app, GEICO sells directly to consumers and often has some of the lowest rates out there, especially if you have a clean driving record. Managing your policy on their mobile app is refreshingly simple.
- Wawanesa: This one might not be a household name nationwide, but Wawanesa is a big deal in California. They are known for offering fantastic prices to drivers who have kept a spotless record for several years. They can be selective, but they absolutely reward safe drivers with major savings.
- Mercury: As a California-based insurer, Mercury knows this state inside and out. They often deliver very competitive pricing, particularly for good drivers who might not have that "perfect" profile. Their strong network of local agents is a big plus for finding every last discount.
In California, GEICO consistently comes in as one of the most affordable options for full coverage. Recent data shows an average annual rate of $1,291, which breaks down to $108 a month for a 35-year-old with a clean record. That’s about 57% cheaper than the statewide average of $3,022 and even beats out strong competitors like Mercury ($1,352) and Auto Club of SoCal ($1,472).
How Pricing Stacks Up for Different Drivers
Here's the thing: the "cheapest" company for a 20-year-old student in San Diego is almost never the same as the best choice for a 55-year-old homeowner in Fresno. Every insurer has its own secret sauce—a unique formula for calculating risk.
For example, one company might be pretty forgiving about a single speeding ticket, while another will hike your rates significantly for the same offense. This is exactly why getting multiple quotes is non-negotiable. An insurer that looks expensive on the surface might offer a unique discount—maybe for your job or for bundling with renters insurance—that suddenly makes them the most affordable option for you. It all comes down to the specifics of your situation.
Finding the Right Fit Beyond Price
A low premium is great, but it shouldn't be the only thing you look at. Let's be honest, a rock-bottom price doesn't mean much if the company has terrible customer service or makes filing a claim a total nightmare.
Before you sign on the dotted line, take a few minutes to check a company's financial stability and customer satisfaction ratings. You want an insurer who will actually be there for you when you need them, not just the one with the cheapest ad. The real win is finding that perfect balance between a price you can afford and the reliability you can count on.
This is especially critical in big, congested metro areas. For instance, the factors that shape the best auto insurance in Los Angeles are often worlds apart from those in rural counties due to higher traffic and risk.
Ultimately, your goal is to find a provider that truly aligns with your life. A young driver might want a company with a great telematics program to earn discounts, while a family might be focused on bundling home insurance and life insurance to save as much as possible. By starting with the most affordable carriers and then digging into what makes each one special, you can confidently find a policy that delivers both value and peace of mind.
How to Lower Insurance Costs for Teen Drivers
If you're a California parent, get ready for some serious sticker shock when you add your teenager to your car insurance. It’s nothing personal; it’s all about the numbers. To an insurer, a young, new driver is a big question mark, and that uncertainty translates into some of the highest premiums you’ll ever see.
But don't panic. Those sky-high rates aren't carved in stone. You can't fast-forward their age, but you can be smart and strategic to find the cheapest car insurance in California for your family's new driver. It all comes down to being proactive and knowing where the real savings are.
Rule #1: Keep Them on Your Family Policy
The single biggest money-saving move you can make is keeping your young driver on your policy. The price gap between adding them to your plan versus them getting their own is massive. A teen trying to get a standalone policy is viewed as a huge risk, and the premium will be painfully high to match.
It’s like getting a family-plan discount on your cell phone bill. By bundling your teen with more experienced, lower-risk drivers (that's you!), the overall risk gets watered down, and the insurance company can offer a much more palatable rate. Forcing them to go it alone is a financial nightmare. Just look at the numbers: the average 18-year-old pays a jaw-dropping $8,113 per year for their own policy, which is 28% higher than the state average.
Not All Companies Treat Teen Drivers the Same
Insurance companies don't have a universal formula for teen drivers. Some are much more forgiving—and affordable—than others, which makes shopping around absolutely critical. While California teens face some of the steepest rates in the country, you can find pockets of significant savings.
For example, Wawanesa is often a great bet for the youngest drivers, with 16-year-olds seeing average rates around $177 per month—that's 36% less than the state average for that age. As they get a bit older, the best option can change. By age 19, GEICO frequently takes the lead with rates around $111 per month, saving a driver 32%, or $531 a year, compared to the average. It pays to learn more about how different insurers rate young drivers in California to find the right match.
The Discounts You Absolutely Must Ask For
After you've picked the right policy and company, discounts become your most powerful tool. Every little bit helps, and most teen drivers will qualify for at least one of these.
A quick pro-tip: Don't assume your insurance company will automatically apply these discounts. You almost always have to ask for them. A little initiative here can save you a lot of money.
Here are the top discounts to chase down for your young driver:
- Good Student Discount: This is the easiest win. Most insurers will knock off a hefty chunk—often up to 25%—for high school or full-time college students who keep up a "B" average (3.0 GPA) or higher.
- Defensive Driving Course: Proving your teen is committed to safety pays off. Completing an approved driver's ed or defensive driving course signals responsibility to an insurer, and many will reward you with a nice discount.
- Safe Driving Telematics: This is where modern tech meets old-school savings. Usage-based programs use a smartphone app or a small plug-in device to track actual driving habits. If your teen demonstrates safe behaviors like smooth braking and avoiding late-night driving, you can earn some really significant discounts based on their real-world skills.
Your Action Plan for Lower Car Insurance Premiums
Knowing what affects your insurance rate is a great start, but that knowledge is only powerful if you use it. Now, let's turn theory into actual savings. Finding the cheapest car insurance in California isn't about luck; it's about being proactive and not just accepting whatever renewal notice lands in your mailbox.
Here’s a practical checklist you can use to start chipping away at your bill. It’s time to stop thinking of your policy as a fixed cost and start treating it like a flexible plan you can fine-tune.
Conduct an Annual Policy Review
Life moves fast, and your insurance policy needs to keep up. The perfect coverage you had last year might be a poor fit today, and that means you could be overpaying. Make it a yearly habit—like a financial check-up—to give your policy a thorough look.
Pull out your documents and ask yourself a few simple questions:
- Is my mileage still accurate? A new remote job or a shorter commute means fewer miles on the road. That can easily translate into a low-mileage discount.
- Do I still need full coverage? If you’re driving an older car, its market value might be less than what you’re paying for collision and comprehensive coverage. At some point, it just doesn't make financial sense anymore.
- Have I made any safety upgrades? Did you install a new anti-theft device or an advanced braking system? Even small improvements can earn you a discount.
Proactively Ask for Every Available Discount
Here’s an industry secret: insurance companies have a ton of discounts available, but they don't always volunteer them. You have to ask. Don't be timid—get your agent on the phone and run through a list of possibilities.
The easiest win is usually bundling. Combining your auto insurance with your home or renters policy from the same company can unlock some of the biggest savings. Beyond that, ask about discounts for being a good driver, paying your annual premium all at once, or even for being a member of certain alumni associations or professional groups.
The most expensive mistake you can make is assuming you're already getting the best deal. A single phone call to review your discount eligibility can easily save you hundreds of dollars over the life of your policy.
Adjust Your Deductible Strategically
Your deductible is simply the amount of money you agree to pay out-of-pocket on a claim before the insurance company steps in. It has a direct, see-saw relationship with your premium: when one goes up, the other goes down.
A higher deductible means a lower premium. Think about bumping your deductible up from $500 to $1,000. For many drivers, this one tweak can create a noticeable drop in their collision and comprehensive costs. The key is making sure you have that higher amount stashed away in an emergency fund, just in case. It's a calculated risk that pays off month after month for safe drivers.
Let an Independent Agent Shop for You
Comparing quotes is the single most effective way to ensure you're not overpaying, but let's be honest—it's a hassle. This is where an independent insurance agency like Mai & Associates really shines. Instead of you spending hours filling out the same information on a dozen different websites, a licensed agent does all the legwork.
We have access to rates from a wide range of top-rated insurance carriers, including some that don't sell directly to consumers. This saves you an incredible amount of time and often uncovers rates and coverage combinations you wouldn't find on your own. When you're ready to see how the market stacks up for you, you can get a quick insurance quote online and let us handle the comparison shopping.
Frequently Asked Questions About California Car Insurance
Let's face it, diving into the world of auto insurance can bring up a lot of questions. Getting straight answers is the first step toward making a smart choice and finding the cheapest car insurance in California that actually fits your life. Here are some of the most common things drivers ask us.
How Often Should I Shop for New Quotes?
Treat shopping for car insurance like an annual financial check-up. You should absolutely get fresh quotes at least once a year, and always before your current policy is set to renew. Insurance rates are constantly in flux, and the company that gave you the best deal last year might not even be competitive for you today.
It’s also a good idea to shop around anytime you have a major life change. Did you move to a new zip code? Buy a new car? Get married? Add a teenager to your policy? All these events can dramatically shift your rates, often opening up new ways to save.
Will One Speeding Ticket Ruin My Rates?
One ticket isn't going to ruin your rates forever, but you'll probably feel the sting for a few years. Insurers see any moving violation, even a minor one, as a sign of higher risk. You can expect your premium to go up for about three years.
The exact size of that increase really depends on the insurance company, how clean your record was before the ticket, and how fast you were going.
Is It Cheaper to Pay My Premium Annually or Monthly?
Paying your full six-month or annual premium all at once is almost always cheaper. Why? Because most carriers tack on a small administrative or installment fee to each monthly payment. While breaking it up into monthly payments can be easier on the budget, paying in full can save you a decent chunk of change over the policy term if you have the cash on hand.
How Does Bundling Save Me Money?
Bundling is easily one of the most reliable ways to get a discount. When you buy multiple policies—like your auto insurance and home insurance or renters insurance—from the same company, they reward that loyalty with a multi-policy discount.
Insurers love bundled customers. They see you as more stable and less likely to switch carriers, so they're willing to offer a pretty hefty price break to keep your business. This strategy not only simplifies your life but can also save you anywhere from 5% to 25% on your total insurance bill.
It's a classic win-win: you get a lower price, and they get to handle more of your insurance needs. For more answers to common questions, you can also check out our comprehensive California insurance FAQ page.
Finding that sweet spot between great coverage and a great price can feel overwhelming, but you don't have to figure it out alone. The licensed agents at Mai & Associates live and breathe the California insurance market. We do the heavy lifting for you, comparing quotes to find the best rates for your auto, home, renters, and life insurance. Secure your free, no-obligation quote today!