Affordable SR22 Insurance in California for 2026
So, you’ve been told you need an SR22. The first thing most people think is that it’s some special, expensive type of insurance. Let's clear that up right away.
An SR22 isn't insurance at all. It's simply a form—a certificate, really—that your insurance company files with the California DMV on your behalf. Its purpose is to prove you're carrying the state's required liability coverage for your car insurance. Think of it as a flag on your file that tells the DMV you're being monitored.
What An SR22 Really Means For California Drivers
When a court or the DMV orders you to get an SR22, it’s because a specific incident has re-categorized you as a "high-risk" driver. This form essentially puts your California insurance status under a microscope.
From that moment on, your insurance carrier is legally obligated to act as a watchdog for the DMV. If your policy is canceled, lapses for non-payment, or expires, they have to report it immediately. This system of continuous monitoring is the whole point of an SR22 filing.
Why Would You Need An SR22?
This isn't something that happens for a simple speeding ticket. An SR22 requirement is triggered by significant driving violations that make the state question your ability to drive responsibly.
Here are the most common reasons a California driver gets hit with an SR22 mandate:
- A DUI or DWI conviction is the most frequent trigger.
- Being found guilty of reckless driving.
- Causing an accident while you were uninsured.
- Racking up too many points on your driving record in a short period.
- Getting caught driving on a suspended or revoked license.
If you're in one of these situations, the SR22 is the non-negotiable key to getting your driver's license reinstated. You simply can't get back on the road legally without it.
Here’s the bottom line: An SR22 is not a suggestion—it's a legal order from the California DMV. If you don't file it and keep it active, your license will remain suspended indefinitely.
How To File An SR22 In California
You have a couple of common paths to meet this requirement. Your choice depends on whether you own a vehicle and what makes the most financial sense for your situation.
This table breaks down the common ways to meet California's SR22 requirement, helping you see which approach is the most practical and affordable for your situation.
Comparing SR22 Options for California Drivers
| Filing Option | Best For | How It Works | Typical Cost Impact |
|---|---|---|---|
| Add to Existing Policy | Vehicle owners who want to keep driving their car. | Your insurer adds the SR22 filing to your current auto insurance policy. This is the most direct method if you already have a car and insurance. | Moderate to high premium increase on your existing policy due to the high-risk designation. |
| Non-Owner Policy with SR22 | People who don't own a car but need to reinstate their license. | You purchase a policy that covers you when you occasionally borrow a car. The SR22 is attached to this non-owner policy. | Generally cheaper than insuring a specific vehicle, but still more expensive than a standard non-owner policy. |
Deciding between these options is a critical first step. A non-owner policy can be a smart, cost-effective solution if you don't have a vehicle, but if you need to drive your own car, you'll have to add the SR22 to a traditional car insurance policy.
The Inevitable Impact On Your Insurance Bill
That "high-risk" label is exactly why your insurance rates are about to go up. To an insurer, an SR22 signals a greater chance you'll be involved in a future claim, and they adjust your premium to reflect that risk. This is why finding affordable SR22 insurance becomes so important.
The cost can vary wildly. In California, which is already one of the priciest states for high-risk coverage, an SR22 policy can easily run over $5,500 annually just for basic liability. The national average is often much lower, which highlights how crucial it is to compare quotes from different carriers who specialize in SR22s.
Even though the SR22 is attached to your California car insurance, this is the perfect time to ask about bundling. Combining your auto insurance with a home insurance, renters insurance, or even life insurance policy can unlock discounts that help soften the financial blow of your overall California insurance costs. Understanding these basics is the first step to navigating the requirement without breaking the bank.
What Really Drives Your SR22 Insurance Cost
When clients first learn they need an SR22, their first question is almost always, "How much is this going to set me back?" The truth is, there's no flat fee. Finding affordable SR22 insurance means understanding the specific details insurance carriers look at to calculate your new rate.
Your premium is a direct reflection of the risk you represent. The biggest factors are the violation that triggered the SR22 requirement, your overall driving history, where you live in California, and which insurance company you ultimately go with.
The Violation Matters Most
From an insurer's perspective, not all SR22-worthy offenses are created equal. The single biggest driver of your new premium is the specific reason you need the filing in the first place.
- A DUI Conviction: This is the big one. It's the most serious offense and will trigger the sharpest rate increase because it signals the highest level of risk.
- Reckless Driving: Still a major red flag, but the premium hike might be slightly less severe than what you'd see with a DUI.
- At-Fault Accident Without Insurance: This demonstrates a lapse in financial responsibility and also brings a significant rate jump.
Put simply, the more dangerous the behavior that led to the SR22, the more you can expect to pay. A driver with a DUI in Los Angeles will always see a steeper cost than someone in Fresno with a single at-fault accident on their record. There's a lot to learn about the impact on car insurance costs after a DUI, and it helps explain why these rates can skyrocket.
Location and Coverage Choices
Believe it or not, your ZIP code has a huge say in your premium. If you live in a dense urban area like San Francisco or Los Angeles—where traffic, theft, and accidents are more common—the base rates for all car insurance are higher. That baseline cost is what your SR22-related increase gets added to.
Your choice between minimum liability and full coverage will dramatically alter your final premium. If you finance or lease your vehicle, your lender will almost certainly require you to carry full coverage, which includes collision and comprehensive protection.
This decision creates a massive cost difference. Looking at data for 2026, the gap is clear. Minimum liability SR22 policies tend to average between $1,368 and $3,000 annually. But if you need full coverage, that cost jumps to between $3,022 and $7,000 per year. In a high-cost state like California, a full coverage SR22 policy can easily push toward that $7,000 mark.
Understanding these key pieces gives you a realistic financial picture. Once you know what’s driving the cost, you can start building a budget and exploring smart ways to find savings—like bundling your auto insurance with home insurance or renters insurance.
How to Secure Your SR22 Insurance Filing
Getting an SR22 filed in California can feel overwhelming, but I promise it's more straightforward than it seems. The key is to break it down into a few manageable actions. Your first move isn't making a frantic phone call—it's getting your ducks in a row.
Before you do anything else, gather your documents. Having everything ready makes the process infinitely faster for your insurance agent. You’ll need your driver’s license number, some basic personal info, and—this is the most important part—the official letter from the DMV or court that states you need an SR22. That piece of paper has all the critical details your agent needs to file everything correctly the first time.
Choose Your SR22 Policy Path
With your information ready, it’s time to decide how you'll get this coverage. This choice is a major driver of your total cost, so it’s worth thinking through.
- Adding to an Existing Policy: If you already have a car and an active auto insurance policy, the simplest path is to ask your provider to add an SR22 filing. Be prepared, though. Many standard carriers don't handle SR22s and might even non-renew your policy because of the new risk.
- Starting a New SR22 Policy: If your current company says no, or if their new quote is sky-high (which happens!), you'll need to find a new policy. This usually means looking for carriers that are comfortable working with high-risk drivers.
- Getting a Non-Owner Policy: What if you don't own a car? You can still get your license back. A non-owner car insurance policy with an SR22 is designed for this exact situation. It gives you liability coverage when you're driving a borrowed vehicle and satisfies the state’s requirement, often for a much lower cost.
This is a common sticking point for many people. If you don't need to insure a specific car, the non-owner policy is almost always the most affordable way to get back on the road.
The Power of Comparison Shopping
Here's the single most effective thing you can do to find affordable SR22 insurance: compare quotes. I've seen rates vary by hundreds, sometimes even thousands, of dollars for the exact same driver and violation. Calling around to different companies one by one is a huge time sink.
This is exactly where working with an independent agency like Mai & Associates pays off. Instead of you spending hours on the phone, our agents do the heavy lifting. We instantly shop your profile across our network of top-rated insurance carriers who specialize in SR22 filings for California insurance.
The key takeaway is that you are not locked into the first quote you receive. By leveraging an independent agent, you gain access to a competitive marketplace designed to find the best possible rate for your specific situation.
Let an Agent Handle the Filing
Once you’ve picked the best policy, the final step is the official filing—and you don't have to do it yourself. Your new insurance agent will electronically submit the SR22 certificate directly to the California DMV on your behalf. In most cases, this is done the very same day.
This electronic submission is what officially tells the state you’re insured again, clearing the way for your license reinstatement. An experienced agent ensures it’s done right away, preventing frustrating delays. They'll also follow up to confirm the DMV has processed the form, giving you total peace of mind.
Curious how we can streamline this for you? You can learn more about our process and get a no-obligation quote to see your options today.
Practical Strategies to Lower Your SR22 Premiums
Getting hit with an SR22 requirement can feel like your insurance costs are spiraling out of control. But you have more power than you think. Finding affordable SR22 insurance isn't about luck; it’s about knowing which levers to pull to bring those premiums back down to earth.
Based on my experience helping hundreds of California drivers, there are several proven tactics that can make a real, immediate difference.
Look for Discounts and Policy Adjustments
Many drivers assume they're disqualified from discounts once they need an SR22. That's simply not true. You have to ask your agent directly, as they won't always be offered upfront.
- Defensive Driving Course: Completing a state-approved course is a clear signal to insurers that you’re serious about safe driving. The result is often a nice, straightforward discount on your auto insurance.
- Good Student Discount: If you or a young driver on your policy keeps up a "B" average or higher, you can often knock a surprising amount off your rate.
- Payment Plans: This is a simple one. If you can afford to pay for your six-month or annual policy all at once, most carriers will give you a discount compared to paying month-to-month.
Another effective strategy is to adjust your policy's deductibles for physical damage (comprehensive and collision). Raising your deductible from $500 to $1,000, for instance, lowers your premium because you're agreeing to cover more of the cost in a claim. Just be honest with yourself—make sure that higher deductible is an amount you could comfortably pay out of pocket if something happened.
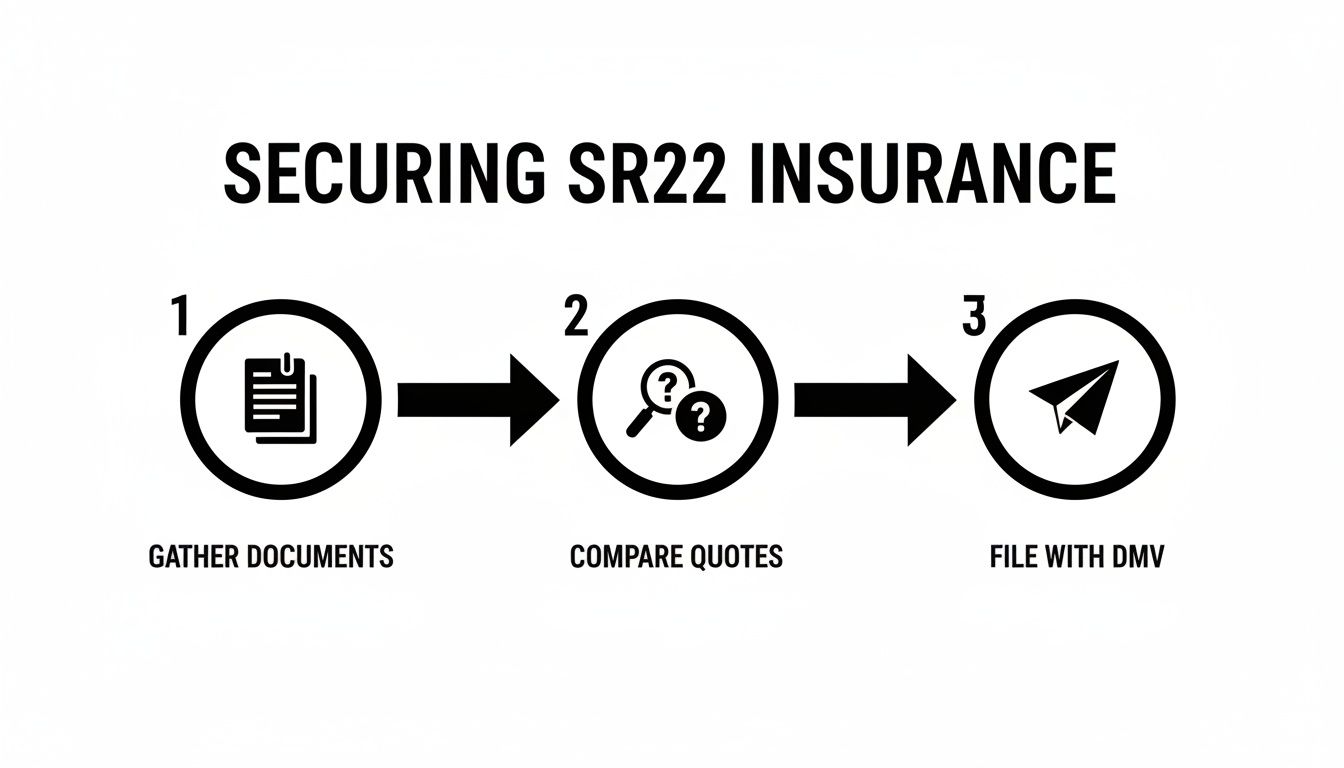
Getting the SR22 filed is a straightforward process once you know the steps. You gather your info, we help you compare quotes, and then we handle the DMV filing for you.
Unlock Serious Savings by Bundling Policies
If there’s one secret weapon for offsetting a high SR22 premium, it's bundling. Insurers love loyalty, and they reward customers who buy multiple policies from them with significant discounts. This is often the single most effective way to save on all your California insurance needs.
By combining your high-risk car insurance with another policy, the savings can effectively cancel out a large portion of the SR22 surcharge.
Think about bundling your auto insurance with:
- Homeowners Insurance: This usually offers the biggest discount.
- Renters Insurance: It’s an inexpensive policy that can unlock a surprisingly valuable auto discount.
- Life Insurance: A smart financial move that can also lower your car insurance bill.
Bundling simplifies your life with a single point of contact for your insurance needs, but more importantly, it unlocks multi-policy discounts that make a huge dent in the cost. It’s the fastest way to get real savings on your entire California insurance package.
It's also important to recognize that the insurance market is always in flux. We saw steady premium hikes from 2020 through 2026, putting extra pressure on high-risk drivers who were already paying more. Working with an independent agency like Mai & Associates is critical in this environment, as we can shop your policy across numerous carriers to find the best rate the current market has to offer. If you're interested in the data behind these trends, you can explore detailed insurance industry analysis on SkyWatch.ai.
Ultimately, the best long-term play is to maintain a perfect driving record from this day forward. Every 24 hours you drive safely is a step toward removing the SR22 and getting back to the lowest possible standard rates.
Partnering with an Expert for Your SR22 Needs
Let's be honest—dealing with an SR22 requirement is a major headache. Trying to figure out the rules, find an insurance company that will even cover you, and then avoid overpaying can feel like a full-time job. It’s confusing and stressful.
This is where having an experienced insurance agent in your corner really changes the game. At Mai & Associates, we’re not just brokers; we’re advocates for California drivers. We take the entire frustrating process off your plate, from finding the right policy to getting the paperwork filed with the DMV.
Your Advocate in a Complicated System
Our licensed agents immediately get to work, shopping our network of top-rated insurance carriers. Many of these companies specialize in SR22s, which means they’re more competitive and understand the nuances. We do all the calling and comparing so you don't have to spend hours repeating your story.
Once we find the best policy for your situation, we handle the electronic SR22 filing directly with the California DMV. We can often get this done the very same day, which is crucial for getting your license reinstated without any delays from common filing errors. Our multilingual support also ensures every detail is handled correctly.
We don't just stop at the filing, though. We look at your whole financial picture to find savings you might not see on your own.
By far, the most effective strategy we use is bundling your policies. When we pair your auto insurance with your home insurance, renters insurance, or even a life insurance policy, the multi-policy discounts are often so significant they can help cancel out the higher cost of the SR22 itself.
This turns a tough situation into a smart opportunity to get better, more comprehensive coverage while actually saving money on your total California insurance portfolio.
Get a Quote and Get Back on the Road
With offices throughout California and the ability to deliver same-day quotes, our goal is simple: find you an affordable SR22 insurance solution that gets you back on the road, legally and with confidence.
Working with an expert gives you more than just a policy; it gives you peace of mind knowing everything was done right. To see how our team can help you navigate this process and find real savings, please contact us today for a personalized consultation. We’re here to help you move forward.
Common Questions About California SR22 Insurance
It's completely normal to have a lot of questions when you're suddenly faced with an SR22 requirement. Frankly, the system can be confusing. To help cut through the noise, we've put together answers to the questions we hear most often from drivers right here in California.
How Long Do I Need an SR22 in California?
For most situations, the state of California will require you to maintain an SR22 for three consecutive years. This is the standard timeframe.
Be aware, though, that the clock can be extended if the original violation was particularly severe or if you get into more trouble while the SR22 is active. It is absolutely essential that your car insurance coverage doesn't lapse—not even for a day. If it does, your insurer is legally obligated to tell the DMV, which could suspend your license all over again and reset your three-year timeline.
Can I Get SR22 Insurance If I Don't Own a Car?
Yes, and this is a situation we see all the time. If you don't own a vehicle but need to get your license back, you can get a non-owner auto insurance policy with an SR22 filing.
This type of policy gives you the required liability coverage for when you’re driving a car you’ve borrowed or rented. It’s a smart and often much cheaper way to satisfy the state's mandate without having to insure a specific vehicle.
Expert Tip: A non-owner policy is one of the best tools for finding affordable SR22 insurance if you don't own a car. It isolates the liability requirement, making it a very direct and cost-effective solution.
What Happens If I Move Out of California?
This is a common point of confusion. Even if you move to a state that doesn’t require SR22s, you are still legally bound to complete California's requirement. You must keep an active insurance policy that meets California’s minimums and maintains the SR22 filing for the entire three-year period.
If you let it lapse, California will suspend your driving privileges. This will almost certainly create a major roadblock when you try to get a new license in your new home state.
Will My Insurer Cancel My Policy?
It’s a possibility. Some insurance companies simply don't want to take on the risk associated with an SR22 filing. If you’re with a "standard" carrier, you might receive a non-renewal notice once they find out.
The good news is that many other insurers specialize in this exact area and are happy to provide coverage. Working with an independent agent gives you a huge advantage here, as we can connect you directly with carriers who understand the situation and offer competitive rates on auto insurance. For more answers like these, check out our detailed FAQ section.
At Mai & Associates, our job is to make this process as painless as possible. We find the right policy, handle the SR22 filing for you, and get you back on the road with confidence. Whether it's for your auto insurance, home insurance, renters insurance, or life insurance, we provide clear answers and competitive rates for all your California insurance needs. Get your no-obligation quote today at https://cahomeauto.com.